IFRS Compliance
in Sharjah
We review your reporting, correct IFRS gaps, and prepare financial statements with the notes and evidence needed for external review.
TRUSTED BY 500+ INDUSTRY LEADERS
- IFRS Standards
- UAE Reporting
- Sharjah, UAE
Reporting That Holds Up
Get figures that can be explained clearly to auditors, banks, shareholders, and your own management.
Fewer Late Changes
IFRS issues are found before external review, reducing the risk of rushed reclassifications, missing disclosures, and avoidable back-and-forth.
Clearer Financial Position
Management receives statements that separate operating performance, obligations, assets, and cash movement in a consistent reporting format.
Better External Discussions
Properly prepared statements give lenders, investors, auditors, and business partners a more reliable basis for reviewing your business.
Repeatable Reporting Process
Documented accounting treatment helps your finance team handle recurring transactions consistently in future reporting periods.
IFRS Reporting Work
The engagement is built around the records, transactions, and reporting deadline in front of you.
IFRS Gap Review
Review existing records, policies, balances, and disclosures against relevant IFRS requirements.
Accounting Policy Review
Assess accounting policies for revenue, inventory, leases, provisions, and financial instruments.
IFRS Adjustments
Prepare proposed journal entries, reclassifications, and supporting schedules for identified reporting gaps.
Financial Statements Preparation
Prepare IFRS-format statements, notes, comparative figures, and supporting disclosure schedules.
Disclosure Checklist Review
Check notes and disclosures against applicable IFRS presentation and disclosure requirements.
Audit Support
Organize working papers and explain accounting treatment during external auditor queries.
IFRS Reporting Practice
Ahmed Mahfoudh Chartered Accountants & Auditors handles IFRS compliance as a working finance exercise, not a template exercise. The work begins with your trial balance, contracts, schedules, and prior financial statements. From there, I identify the accounting treatment that needs attention, document the reasoning, and prepare the adjustments and disclosures required for your reporting package. IFRS Standards are required for financial statements under the UAE Commercial Companies Law, so the details need to stand up when reviewed.
How IFRS Work Is Handled
Many businesses only discover reporting gaps after their auditor asks for evidence.
We start with the actual records
The review starts with source documents, ledgers, contracts, fixed-asset schedules, lease details, and prior statements. That matters because an IFRS conclusion without the underlying transaction evidence is difficult to support during an audit or lender review.
Adjustments come with reasoning
Proposed entries are not sent as unexplained numbers. Each significant adjustment is linked to the relevant transaction, accounting treatment, and supporting schedule, so your finance team can understand what changed and why it belongs in the statements.
Disclosure work is not skipped
A correct trial balance alone does not produce IFRS-compliant financial statements. The notes, accounting policies, comparative information, and material disclosures are reviewed alongside the face of the statements before the reporting file is finalized.
IFRS Reporting Team
Practical support for finance teams preparing statements in Sharjah.
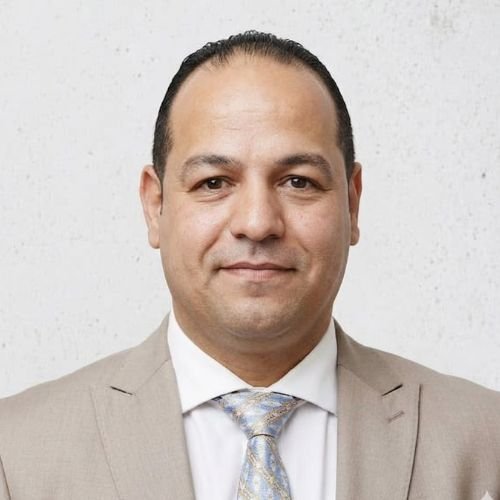
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
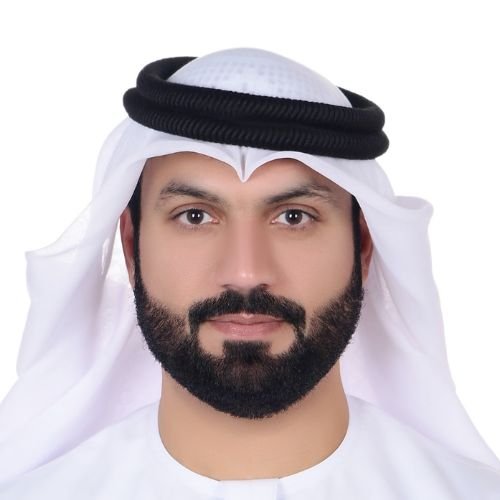
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
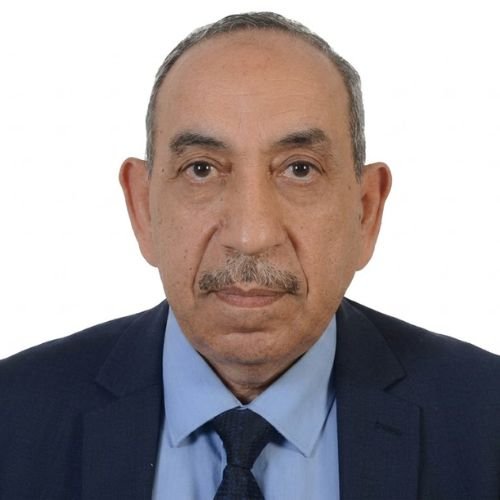
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
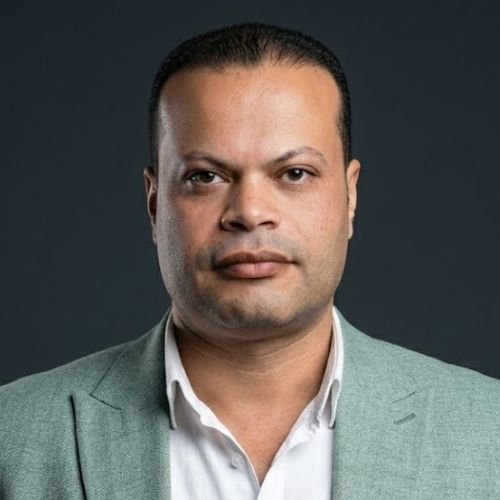
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
Feedback From Sharjah Finance Teams
These are finance leaders and business owners who needed reporting they could present externally.
“Our financial statements are now accurate, consistent, and ready for external review without last-minute adjustments.”
“They explained each requirement clearly and delivered clean, compliant financials for our Sharjah business.”
“The quality of our financial statements improved and supports better discussions with banks and partners.”
“Complex IFRS rules became workable processes, while our statements remained useful for management decisions.”
“From gap analysis to reporting, the work gave us greater confidence in figures presented externally.”
“Their IFRS compliance work raised our reporting standard and made audit processes much smoother.”
IFRS Compliance Questions Answered
The key points to settle before your reporting deadline arrives.
Is IFRS required in Sharjah?
IFRS Standards are required for financial statements under the UAE Commercial Companies Law. Specific free-zone rules, lender requirements, and audit terms may add further reporting obligations.
What does an IFRS review cover?
A review can cover accounting policies, balances, transaction treatment, journal adjustments, financial statement presentation, and disclosures. The exact scope is set after reviewing your trial balance and the reporting period.
How long does IFRS compliance take?
Timing depends on the number of entities, transaction volume, record quality, and unresolved accounting issues. The work should be planned backward from your audit fieldwork or financial-statement issue date.
Can you fix prior-year errors?
Yes, material prior-period errors may require retrospective correction under IAS 8, including restated comparative figures and clear disclosure of the correction. The treatment depends on whether the information was available when earlier statements were prepared.
Do IFRS statements affect corporate tax?
They can. UAE Corporate Tax applies at 9% to taxable income above AED 375,000, and accounting records support the calculation of taxable income, subject to tax-law adjustments.
What documents will you need?
Usually this includes the trial balance, general ledger, bank reconciliations, contracts, invoices, asset register, inventory records, lease information, and previous financial statements. Missing records can delay the review and create audit evidence gaps.
What happens if disclosures are missing?
Missing disclosures can lead to auditor queries, qualification risks, or delayed financial statement issuance. IFRS requires disclosures that help users understand material accounting policies, estimates, risks, and significant balances.
Still have questions? We're here to help.
Call Us Now