VAT Consultants
in Dubai
Get the VAT treatment, evidence and return right before submission. We handle registration, filings, transaction advice, corrections, refund claims and FTA correspondence.
13+ YEARS OF UAE TAX AND AUDIT EXPERIENCE
- FTA Tax Agents
- Transaction-Level Review
- Deadline Monitoring
Get Each VAT Position Right
VAT problems usually begin with one incorrectly treated sale, purchase, import or credit note.
Correct Tax Treatment
Sales and purchases are classified using the transaction facts, preventing assumptions from spreading across every return period.
Supported Input Claims
Recoverable VAT is backed by valid invoices, business use and payment records before it enters the return.
Fewer Filing Surprises
Ledger reconciliations identify missing invoices, duplicate entries and unreported adjustments before the 28-day filing deadline arrives.
Usable Answers
Written advice explains the VAT treatment, relevant facts and records needed by the employees processing the transaction.
Visible VAT Exposure
Errors are quantified by tax period, helping management decide whether return correction, voluntary disclosure or further review is required.
Recoverable Credit Control
Refundable and carried-forward balances are monitored before documentation gaps or statutory time limits place recovery at risk.
VAT Work That Gets Filed
Support covers routine compliance and the transactions that cannot be resolved by applying five percent automatically.
VAT Registration
Assess eligibility and prepare individual, group, amendment or registration-exception applications.
VAT Return Filing
Reconcile VAT accounts, prepare return boxes and submit approved figures through EmaraTax.
Transaction VAT Advice
Determine place, date, value and rate of supply for specific transactions.
Input Tax Review
Test purchase VAT eligibility, invoice evidence, business use and apportionment calculations.
VAT Refund Claims
Reconcile credit balances and prepare refund schedules with supporting documents.
VAT Health Check
Review completed periods for reporting errors, unsupported claims and missed adjustments.
Voluntary Disclosure Support
Quantify prior-period errors and prepare the correction method required under current rules.
VAT Deregistration
Assess cessation or threshold conditions and prepare the EmaraTax deregistration application.
FTA Case Support
Prepare factual responses for information requests, clarifications, audits and VAT assessments.
VAT Advice Backed by Accountants
Ahmed Mahfoudh Chartered Accountants & Auditors has more than 13 years of UAE tax, accounting and audit experience. Our Dubai practice includes FTA-registered tax agents who connect VAT advice to invoices, contracts, customs records, ledgers and filed returns. We support routine compliance as well as transaction-specific questions involving imports, exports, free zones, mixed supplies and input tax recovery. Every filing remains subject to client approval, with reconciliations and supporting schedules retained as part of the working file.
VAT Starts With the Transaction
The recurring mistake is preparing return boxes before confirming what the underlying supplies actually were.
Turnover Is Mapped Before Registration
We separate taxable, zero-rated, exempt and outside-scope amounts before testing the AED 375,000 threshold. The previous 12 months and expected next 30 days are both considered, so registration advice is based on the statutory test rather than annual revenue alone.
Contracts Decide More Than Invoices
An invoice cannot correct the wrong VAT treatment in a contract. We examine what was supplied, where the parties belong, when the supply occurred, who receives it and whether another party accounts for tax under the reverse-charge mechanism.
Zero-Rated Does Not Mean Exempt
Both may produce an invoice without five percent VAT, but the input tax result differs. We document why the supply qualifies for zero rating or exemption and check whether the chosen treatment is supported by the required evidence.
Input VAT Follows Business Use
A supplier invoice is only the starting point. We examine whether the purchase supports taxable activities, whether the invoice is valid, when recovery conditions were met and whether blocked, private or mixed-use expenditure requires exclusion or apportionment.
Every Return Reconciles to Accounts
Output tax, input tax, imports, reverse-charge entries, credit notes and prior adjustments are matched to the accounting records. Unexplained differences remain on the reconciliation until corrected instead of being forced into a return box to meet the deadline.
Refund Balances Are Properly Aged
The 2026 VAT amendments introduced a five-year limitation affecting the use and refund of excess recoverable tax. We identify when balances arose, test their support and distinguish genuine recoverable VAT from ledger balances created by posting errors.
Errors Are Corrected Openly
We quantify the tax effect, identify affected periods and determine the correction route under the rules applying when the error is discovered. Management receives the calculation and supporting explanation before any revised return or voluntary disclosure is submitted.
Advice Leaves an Evidence Trail
Material positions are recorded with the transaction facts, conclusion, legal basis and required documents. This gives finance employees a repeatable treatment and provides an explanation if the FTA later asks why the position was taken.
One Calendar Controls Every Filing
EmaraTax periods, internal cut-off dates, document requests, review dates and payment deadlines are tracked together. The person approving the return sees unresolved matters before submission, not after the 28-day statutory deadline has passed.
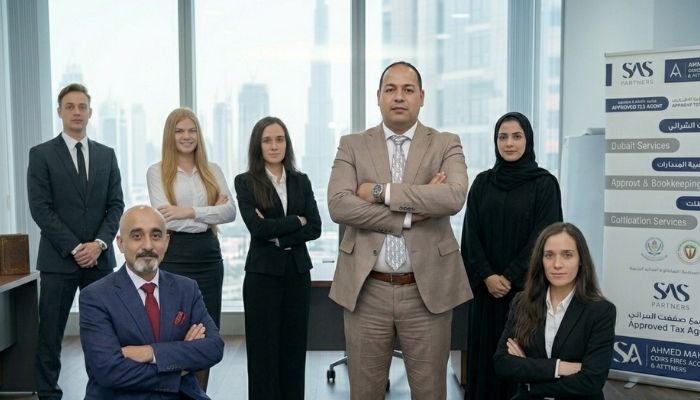
Specialists in UAE VAT Transactions
Tax agents and accountants work from the same invoices, ledgers, contracts and return reconciliations.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Dubai Finance Teams Say
These finance managers, accountants and business owners deal with VAT decisions throughout the year.
“Accurate quarterly returns filed on time. Their input tax advice has kept our records clean and aligned with FTA requirements.”
“They handled our registration and monthly VAT calculations carefully. Clear guidance removed uncertainty and made the process straightforward.”
“Strong knowledge of UAE VAT rules. Complex transactions were reviewed correctly and explained in practical terms.”
“They identified and corrected VAT risks early, giving us greater confidence in the positions reported to the authority.”
“Their help with input tax claims and documentation improved our recovery process and reduced the risk of future assessments.”
“Professional, responsive and consistently accurate. Their VAT consultancy provides clear advice and reliable filing support.”
Dubai VAT Questions Before Filing
The correct answer depends on the transaction, documentation and tax period—not the invoice description alone.
What is the UAE VAT rate?
The standard UAE VAT rate is 5%. Certain qualifying supplies are zero-rated at 0%, while specified supplies are exempt.
When is VAT registration mandatory?
A UAE-resident business must register when taxable supplies and imports exceed AED 375,000 during the previous 12 months or are expected to exceed it within 30 days.
What is the voluntary registration threshold?
Voluntary registration may be available when taxable supplies, imports or taxable expenses exceed AED 187,500 during the previous 12 months or are expected to exceed it within 30 days.
Does the threshold apply to foreign businesses?
The AED 375,000 threshold does not apply to a non-resident making taxable UAE supplies where no other UAE person is responsible for accounting for the VAT.
Do zero-rated sales count toward registration?
Yes. Zero-rated supplies are taxable supplies and generally count toward the registration threshold, while exempt and outside-scope supplies are excluded.
Does total company revenue determine registration?
Not by itself. The calculation considers taxable supplies and relevant imports, while exempt income, outside-scope amounts and qualifying one-off capital asset disposals may receive different treatment.
How quickly must we register?
The application deadline depends on whether the previous-12-month or next-30-day test caused the obligation. The relevant dates and turnover calculation should be established immediately after a threshold is crossed.
Can zero-rated businesses avoid registration?
A business making exclusively zero-rated supplies may request an exception from VAT registration. Approval is at the FTA’s discretion and does not apply once standard-rated supplies begin.
Is appointing a tax agent mandatory?
No. Businesses may manage VAT directly, but only an FTA-registered tax agent appointed through the approved process can formally act as a tax agent before the authority.
When is a VAT return due?
The VAT return and related payment are generally due within 28 days after the end of the assigned tax period.
Are VAT returns monthly or quarterly?
The FTA assigns the tax period shown in the EmaraTax account. Businesses must follow that assigned monthly or quarterly cycle unless the authority approves a change.
Who approves the VAT return?
The taxable person remains responsible for the filed return. We prepare the reconciliation and draft figures, but submission follows approval from the authorised client representative.
What records are needed for filing?
Required records normally include sales invoices, purchase invoices, credit notes, import documents, reverse-charge entries, payment records and general-ledger reports for the tax period.
When must tax invoices be issued?
A tax invoice for a taxable supply must generally be issued within 14 calendar days from the date of supply, subject to the applicable invoicing rules.
Still have questions? We're here to help.
Call Us Now