External Audit Services
in Dubai
We examine your annual financial statements, test the supporting evidence and issue an independent audit opinion for the intended authority or stakeholder.
13+ YEARS OF UAE AUDIT EXPERIENCE
- DDA Approved
- ISA Audits
- IFRS Reporting
Accounts Others Can Rely On
An independent opinion gives shareholders, authorities and lenders a tested basis for assessing your financial statements.
Accepted Reporting
Auditor eligibility and submission requirements are checked before engagement, reducing the risk of presenting an unusable report.
Independent Credibility
Shareholders, lenders and investors receive an opinion from auditors who aren’t responsible for preparing or managing the underlying accounts.
Fewer Filing Delays
A defined request list, reporting timetable and early issue log keep missing records from appearing only at sign-off.
Defensible Balances
Material account balances are supported through reconciliations, confirmations, documents, analytical procedures and other appropriate audit evidence.
Visible Reporting Issues
Material misstatements, unsupported estimates and disclosure gaps are raised with management before they affect the final audit opinion.
External Audit Engagements
The required report depends on your legal structure, licensing authority, reporting framework and intended recipient.
Annual Statutory Audit
Examining annual financial statements and issuing an independent opinion under International Standards on Auditing.
Mainland Company Audit
Auditing LLC and joint-stock company accounts under applicable UAE company reporting requirements.
DDA Entity Audit
Preparing external audit reports for entities requiring an auditor approved by the DDA.
Free-Zone Company Audit
Auditing annual accounts against the submission rules of the relevant free-zone authority.
Group Consolidation Audit
Examining consolidated statements, eliminations, subsidiaries and group-level financial reporting adjustments.
Component Audit Reporting
Performing specified work for a parent company or overseas group auditor.
Bank Requested Audit
Providing audited financial statements requested for financing, covenant reviews or facility renewals.
Special-Purpose Audit
Auditing financial statements prepared for a defined contractual or stakeholder reporting purpose.
Liquidation Audit
Examining final accounts needed during company closure, liquidation or authority deregistration procedures.
Dubai External Audit Credentials
Ahmed Mahfoudh Chartered Accountants & Auditors is a Dubai-based practice with more than 13 years of UAE audit experience and approval from the Dubai Development Authority. External audits are conducted using International Standards on Auditing, with financial statements assessed against the applicable IFRS framework. Before accepting an assignment, the intended report user and authority requirements are identified. The audit team then sets materiality, tests relevant evidence, evaluates misstatements and determines the appropriate opinion without promising the result in advance.
How Your Opinion Is Reached
The costly mistake is appointing an auditor before checking eligibility, records, deadlines and possible reporting issues.
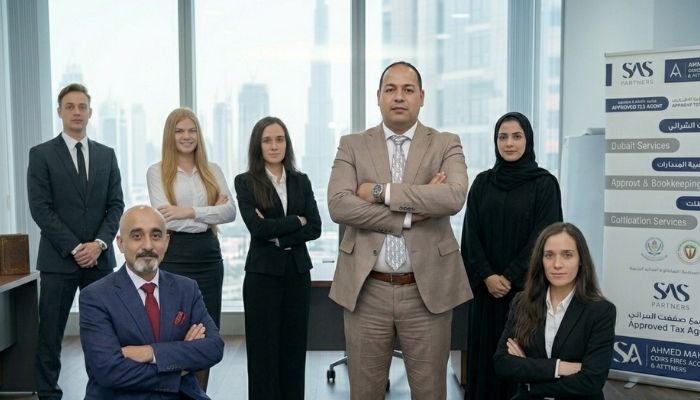
Report Acceptance Is Checked First
Different Dubai authorities maintain their own auditor and submission requirements. We identify the report recipient, company jurisdiction, financial period and required format before engagement. If separate authority approval is required, eligibility must be confirmed before audit work begins.
Requests Link to Financial Balances
The document request isn’t a generic checklist sent without context. Required schedules, confirmations, contracts and transaction support are mapped to relevant statement balances, disclosures and audit assertions, making it clearer why each item is needed.
Material Risks Shape the Fieldwork
An external audit doesn’t test every transaction. We establish materiality, understand the business and identify areas where a material misstatement could occur. Testing is then directed toward those risks using samples, confirmations, recalculation, inspection and analytical procedures.
Difficult Issues Surface Before Sign-Off
Unsupported balances, accounting disagreements and missing disclosures are discussed when identified. Management receives time to provide further evidence or adjust the statements. Waiting until the final report to raise a known qualification risk helps nobody.
Independence Limits Certain Assistance
Management remains responsible for the accounts, estimates and financial statement approval. We can explain audit requirements and discuss proposed corrections, but the external auditor can’t take over management decisions and then independently audit those same decisions.
No Opinion Is Promised
The expected result isn’t agreed as a condition of appointment. The opinion follows the evidence. Material unresolved issues may lead to a qualified opinion, adverse opinion or disclaimer rather than an unmodified report.
Control Findings Stay Separate
Significant control observations can be documented in a management letter with their implications and recommendations. That letter supports operational improvement, but it doesn’t replace the formal opinion on the financial statements.
Auditors Signing Your Report
The engagement team plans, tests, reviews and concludes before the authorised auditor approves the opinion.
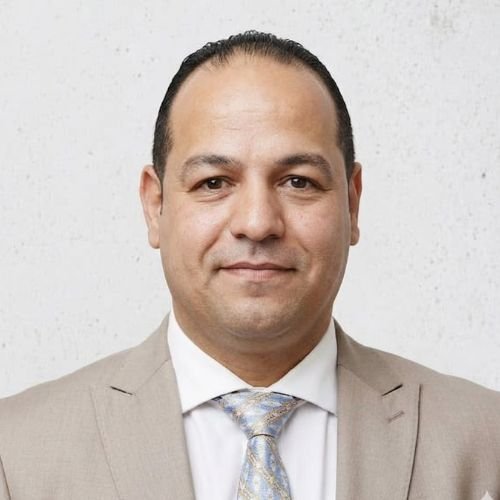
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
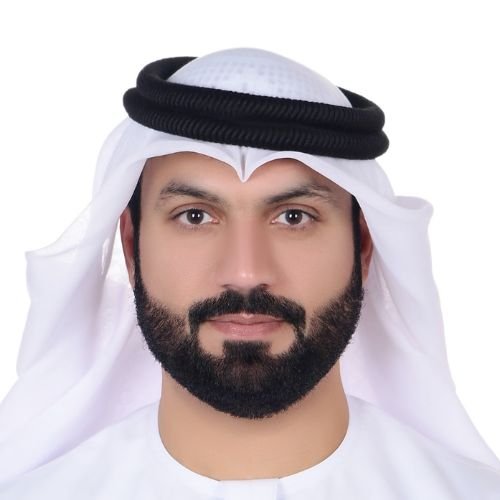
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
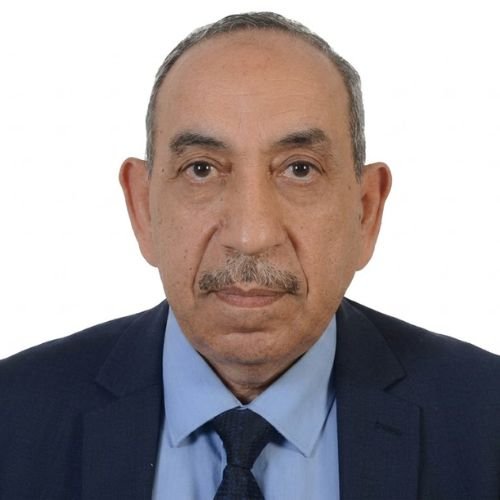
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
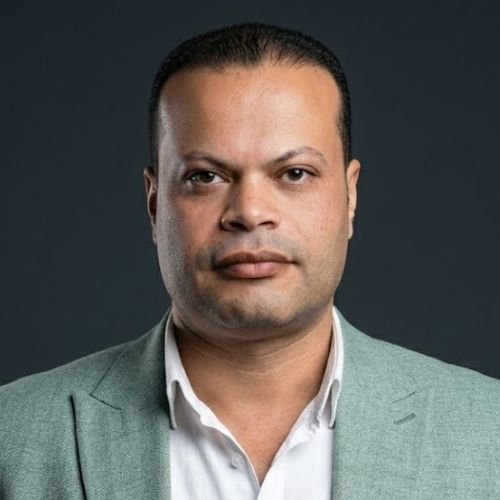
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Dubai Finance Leaders Report
These directors and controllers needed independent financial statements for authorities, banks, investors or group reporting.
“The external audit resulted in a clean opinion. The team remained independent and delivered a clear, well-supported report on time.”
“From planning to sign-off, the process remained organised and transparent. Questions were relevant, fieldwork was efficient and communication stayed consistent throughout.”
“The external audit strengthened our credibility with banks and investors. Their technical knowledge produced a report meeting the international standards expected in Dubai.”
“The auditors respected our daily operations, explained findings clearly and delivered the final report without delay. I appreciated their balanced approach.”
“Beyond statutory requirements, their audit highlighted realistic improvements in documentation and controls that have already strengthened our internal processes.”
“Independent, thorough and reliable. They delivered a credible report on schedule and maintained clear communication at every stage.”
External Audit Questions Answered
Know what is required, what auditors test and what can delay the signed report.
Is an external audit mandatory in Dubai?
Federal Decree-Law No. 32 of 2021 requires UAE limited liability and joint-stock companies to appoint one or more auditors. Free-zone entities must also follow the audit rules of their licensing authority.
Which businesses need audited accounts for Corporate Tax?
Ministerial Decision No. 84 of 2025 requires audited financial statements when a taxable person’s revenue exceeds AED 50 million during the tax period. Qualifying Free Zone Persons must also maintain audited statements.
Do Qualifying Free Zone Persons need annual audits?
Yes. A Qualifying Free Zone Person must prepare and maintain audited financial statements regardless of its annual revenue.
Can any auditor sign a Dubai audit report?
No. The auditor must hold the registrations required for the assignment, and some authorities accept reports only from firms on their approved list. DDA-regulated entities therefore require a DDA-approved auditor.
How long does an external audit take?
A typical SME audit may take two to four weeks after complete schedules and evidence are supplied. Multiple entities, inventory locations, unresolved balances or late confirmations extend the timetable.
How much does an external audit cost?
Fees reflect revenue, assets, transaction volume, locations, group structure, reporting framework and record quality. The quotation is issued after the financial period, intended report user and engagement scope are confirmed.
What records should we prepare?
Auditors normally request the trial balance, financial statements, general ledger, bank reconciliations, receivable and payable ageing, inventory records, contracts, tax returns, payroll reports and supporting documents.
Do you audit every transaction?
Usually not. International Standards on Auditing permit risk-based testing and sampling because the objective is reasonable assurance that the statements are free from material misstatement.
What is audit materiality?
Materiality is the level at which an omission or misstatement could reasonably influence users of the financial statements. It is set during planning and reconsidered when circumstances change.
Does an audit guarantee a clean opinion?
No. The auditor’s conclusion depends on the statements and evidence available. An unmodified opinion can’t be promised before fieldwork and review are complete.
What audit opinions can be issued?
The possible outcomes include an unmodified opinion, qualified opinion, adverse opinion or disclaimer of opinion. The result depends on the materiality and pervasiveness of identified issues or evidence limitations.
What if important documents are missing?
Management receives a list of outstanding evidence and a deadline for submission. If sufficient appropriate evidence can’t be obtained, the limitation may modify the opinion or prevent the auditor from expressing one.
Who prepares the financial statements?
Management is responsible for preparing and approving the financial statements, selecting accounting policies and maintaining records. The external auditor independently examines those statements and reports a conclusion.
Are IFRS and ISA the same?
No. IFRS governs how financial statements are prepared, while International Standards on Auditing govern how the auditor plans, tests, documents and reports the audit.
What is a management letter?
A management letter reports control weaknesses and other observations identified during the audit. It is separate from the signed audit opinion and is generally addressed to management or those charged with governance.
Can we change our external auditor?
Yes, subject to company, authority and professional requirements. The incoming auditor may communicate with the previous auditor and must obtain sufficient evidence regarding opening balances under ISA 510.
Can you help submit the final report?
Submission support can be included once the intended authority and filing process are confirmed. Management remains responsible for approving the statements and meeting its statutory deadline.
How long must tax records be retained?
UAE Corporate Tax records and supporting documents generally must be retained for seven years after the end of the relevant tax period.
When is the Corporate Tax return due?
The Corporate Tax return and payment are generally due within nine months after the end of the applicable tax period. The audit should be scheduled early enough to support that filing date.
Still have questions? We're here to help.
Call Us Now