Corporate Governance Audit
in Dubai
We examine how board authority is exercised, documented and monitored, then report gaps in committee oversight, conflicts, disclosures and decision controls.
13+ YEARS OF UAE AUDIT EXPERIENCE
- Board Evidence Review
- Committee Testing
- Conflict Controls
Decisions That Can Be Defended
A governance audit shows whether board oversight works in practice and leaves sufficient evidence behind.
Clear Authority
Directors and executives can see where approval limits overlap, remain undocumented or allow decisions outside the intended chain of authority.
Accountable Committees
Committee mandates, meeting activity and reported outputs reveal whether delegated responsibilities receive meaningful attention throughout the year.
Visible Conflicts
Better declarations and recusal records reduce the risk of interested directors influencing decisions involving suppliers, investments or related parties.
Complete Decision Trail
Proper agendas, papers, minutes and resolutions show why material decisions were taken and who reviewed the underlying information.
Closed Governance Gaps
Prior findings are assigned to accountable owners and tracked until evidence confirms that the agreed corrective action was completed.
Stronger Shareholder Oversight
Clear reporting gives shareholders a factual view of board composition, oversight arrangements and departures from applicable governance requirements.
How Board Oversight Is Tested
The review follows the company’s legal form, regulator, constitutional documents and approved governance framework.
Governance Framework Review
Compare governance policies and structures with applicable legal and regulatory requirements.
Board Composition Assessment
Examine director appointments, independence classifications, skills, terms and declared outside interests.
Committee Effectiveness Review
Test committee mandates, composition, meeting activity, reporting and completed responsibilities.
Delegated Authority Testing
Trace selected decisions through approval limits, reserved matters and authorised signatories.
Minutes and Resolutions Review
Inspect board papers, attendance, deliberations, voting records, resolutions and action logs.
Conflict Controls Review
Examine interest declarations, recusals, registers and approval procedures for conflicted matters.
Related-Party Oversight
Test how related-party proposals are identified, reviewed, approved and disclosed.
Risk Oversight Assessment
Evaluate board supervision of internal controls, compliance, internal audit and enterprise risks.
Governance Disclosure Review
Compare published governance statements with board records and supporting evidence.
Remediation Tracking Review
Verify whether earlier governance findings were assigned, monitored and formally closed.
Auditors Focused on Board Evidence
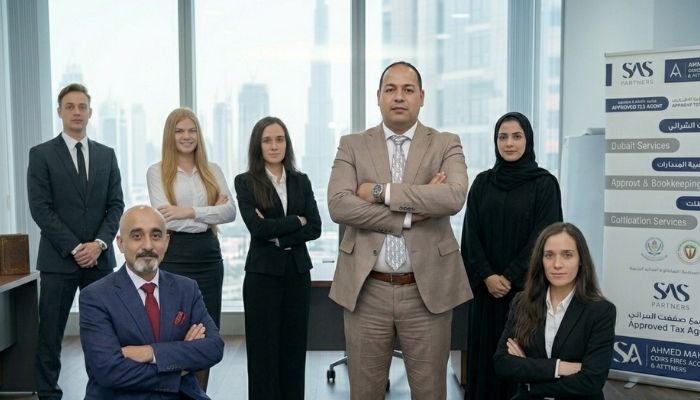
Ahmed Mahfoudh Chartered Accountants & Auditors brings more than 13 years of UAE audit experience to corporate governance reviews. Our Dubai team connects policies and organisation charts to actual approvals, committee records, disclosures and control evidence. The firm is DDA approved. Each assignment uses criteria relevant to the entity, which may include the UAE Commercial Companies Law, the Capital Market Authority Governance Guide, constitutional documents, shareholder agreements, free-zone rules and board-approved policies.
Governance Must Work Beyond Paper
The common mistake is reviewing policy wording without testing whether directors and committees followed it when real decisions were made.
Legal Form Sets the Benchmark
A listed public joint-stock company, mainland private company, regulated financial institution and DIFC entity do not share one governance rulebook. We identify the legal form, regulator, licence conditions and internal governance commitments before setting the audit criteria.
Authority Follows the Decision Trail
Selected investments, contracts, senior appointments, financing arrangements and other reserved matters are traced from proposal to approval. We check whether the correct body decided, the delegated limit was respected and the authorised signatories matched the recorded resolution.
Minutes Must Prove Deliberation
Attendance alone does not demonstrate effective oversight. We compare agendas, advance papers, minutes, dissent, abstentions and follow-up actions to determine whether directors received sufficient information and challenged material matters before reaching a decision.
Independence Is Tested in Substance
A director’s classification is compared with employment, ownership, family, advisory, supplier and other relevant relationships. Potential impairments are reported even when the individual is described as independent in a register or published governance statement.
Conflicted Directors Step Aside
We inspect declarations, meeting records and voting evidence for transactions involving personal or shared interests. The review checks whether the interest was disclosed before deliberation and whether the affected director’s participation was handled under the applicable rules.
Committees Need Verifiable Output
Audit, nomination, remuneration and risk committees are assessed against their approved mandates. Meeting frequency, membership, matters reviewed, recommendations made and escalation to the board are tested through records rather than inferred from committee names on an organisation chart.
Related Parties Stay in View
Related-party governance is followed from identification through review, approval and disclosure. We compare registers with ownership records, director declarations, supplier information and selected transactions to find relationships that may not have entered the formal approval process.
Old Findings Cannot Quietly Expire
Previous internal audit, external audit, compliance and regulatory findings are matched to named owners, target dates and closure evidence. Overdue actions and unsupported closure decisions remain visible in the final report for board consideration.
Findings Carry Different Weight
Regulatory departures, breaches of internal authority, documentation weaknesses and governance improvements are classified separately. This gives the board a clearer basis for prioritising mandatory corrections without treating every observation as the same level of exposure.
Reviewers for Board-Level Controls
Senior audit oversight keeps governance findings factual, proportionate and supported by company records.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Dubai Board Leaders Say
These chairpersons, directors and company secretaries are responsible for making governance work inside their organisations.
“Their independent review assessed board processes, committee effectiveness and policy compliance precisely. The findings were clear and professionally presented.”
“They examined our governance structures, decision-making and disclosures in detail. Every finding was clearly presented and supported by practical observations.”
“Their thorough audit assessed independence, oversight mechanisms and board effectiveness, strengthening confidence among our shareholders and regulators.”
“We received an objective view of our governance strengths and gaps. The report focused on practical improvements rather than theory.”
“Their recommendations improved documentation of board decisions and clarified our conflict-of-interest procedures. We have already implemented the changes.”
“Professional, independent and well structured. Their governance audit provided the assurance and practical insight our board required.”
Before the Governance Review Begins
Applicable rules, board structure and review criteria must be agreed before documents and directors are assessed.
What is a corporate governance audit?
It is an independent assessment of how authority, oversight, accountability and disclosure operate within an organisation. Testing covers both the documented framework and evidence that governance procedures were followed.
Is a governance audit mandatory in Dubai?
Not for every company. The requirement depends on legal form, listing status, sector, regulator, licence conditions and constitutional documents; private companies may commission one voluntarily for shareholders, investors or lenders.
Which rules apply to mainland companies?
Mainland companies are governed by Federal Decree-Law No. 32 of 2021 on Commercial Companies, as amended by Federal Decree-Law No. 20 of 2025. The company’s memorandum, articles and shareholder arrangements also form part of the review criteria.
Who regulates UAE listed companies?
The Capital Market Authority replaced the Securities and Commodities Authority framework from 1 January 2026. Its governance requirements apply alongside market rules for relevant listed issuers.
Which governance guide applies to PJSCs?
The Capital Market Authority publishes the Governance Guide for public joint-stock companies, originally issued under Decision No. 3/Chairman of 2020. Current amendments and company-specific exemptions must be checked for the review period.
Are DIFC companies reviewed differently?
Yes. DIFC entities operate under a separate legal framework, and DFSA-regulated firms must also follow applicable DFSA rules. Mainland corporate requirements should not automatically be used as the sole benchmark.
Do banks follow the same governance rules?
Banks, insurers and other financial institutions may be subject to Central Bank of the UAE governance standards. Their regulatory obligations are assessed separately from the general commercial companies framework.
What documents will you request?
Typical records include constitutional documents, board and committee charters, minutes, resolutions, authority matrices, declarations, registers, policies, risk reports, internal audit reports and governance disclosures.
How is board composition assessed?
The review examines appointment authority, director category, term, skills, independence, outside interests and committee eligibility. Requirements differ according to the entity’s legal and regulatory framework.
How is director independence tested?
Independence is assessed against applicable definitions and relevant relationships, including ownership, employment, family, advisory and commercial connections. A board-approved label is evidence, but not conclusive proof.
Which committees are normally reviewed?
The scope commonly covers audit and nomination and remuneration committees, with risk or other committees included where established or required. Each committee is tested against its own approved mandate.
Are board meetings observed?
Observation can be included if agreed, but documentary testing remains necessary. A meeting observation covers one event, while minutes and action logs show governance activity across the full review period.
Are director interviews confidential?
Interview themes may be reported without attributing comments to named individuals when agreed. Evidence of regulatory breaches or material control failures cannot be omitted merely because it arose during a confidential interview.
What is a delegation-of-authority review?
It compares approval limits and reserved matters with actual decisions. Samples may include contracts, capital expenditure, financing, hiring, procurement and payments approved during the selected period.
Why are board minutes important?
Minutes record attendance, declared interests, deliberation, decisions and assigned actions. Missing or vague minutes make it difficult to demonstrate that directors exercised oversight before approving a material matter.
How are written resolutions tested?
Written resolutions are checked for circulation, voting, signatures, authority and consistency with constitutional documents. Decisions passed outside meetings must still satisfy the applicable approval requirements.
How are conflicts of interest reviewed?
Director and executive declarations are compared with registers, meeting records, ownership data and selected transactions. The audit checks whether disclosure and recusal occurred before the affected decision.
What is related-party governance?
It covers the identification, assessment, approval and disclosure of transactions involving connected persons or entities. Applicable thresholds and approval routes depend on company type and regulator.
Does the audit examine executive pay?
Yes, when remuneration governance is included. Testing may cover policy approval, committee recommendations, performance measures, conflicts and consistency between approved decisions and amounts recorded.
Still have questions? We're here to help.
Call Us Now