VAT Voluntary Disclosure
in Sharjah
Reverse charge on imports, export documentation gaps, and zero-rated versus exempt mix-ups are the errors we see most in Sharjah trading businesses. We correct them through Form 211 before they compound.
VOLUNTARY DISCLOSURES FOR SHARJAH TRADING, IMPORT AND FREE ZONE BUSINESSES
- Form 211 Prepared
- Reverse Charge Reviewed
- Export Evidence Checked
What Correcting This Early Actually Saves
In Sharjah, the errors that trigger disclosure are rarely one-off mistakes, they repeat until someone catches them.
The Lowest Penalty Tier
The percentage penalty on unpaid tax starts at 5% in year one and climbs to 40% after year four. Disclosing now instead of later locks in the lower rate.
One Filing Instead of Several
Only one disclosure can be submitted per tax period, so every error found in that period needs bundling into a single Form 211. Catching them all in one review avoids a second, costlier filing later.
Reverse Charge Errors Caught Before an Audit Does
Reverse charge on imported services is self-assessing and commonly left off entirely, which makes it an early target when the FTA reviews a trading business. Correcting it voluntarily keeps that discovery on your terms.
Zero-Rated and Exempt Supplies Sorted Correctly
Misclassifying a supply between zero-rated and exempt affects both output tax and your recovery ratio, and the error compounds across every period it's repeated in.
Export Documentation That Actually Backs the Zero Rate
Proof of removal and shipping evidence are what keep an export sale zero-rated. Gaps here get closed before they turn a whole period's exports into a liability.
A Correction You Made, Not One the FTA Assessed
An error corrected voluntarily is treated far more favourably than the same error assessed after the FTA finds it independently.
What the Review and Filing Involve
The work between spotting a Sharjah-specific VAT error and having the FTA accept the correction.
Error Review and Impact Calculation
Identifying the mistake in the affected return and calculating the exact tax difference it created.
Threshold Assessment
Determining whether the error clears the AED 10,000 mark for a mandatory Form 211, or can be corrected on the next return instead.
Reverse Charge Reconciliation
Checking imported services for self-assessed VAT that was never declared, a gap that's easy to miss and common among trading businesses.
Zero-Rated and Exempt Classification Review
Reworking supplies that were coded to the wrong category, since the mistake compounds every period it's left uncorrected.
Export Documentation Review
Matching customs and shipping evidence against export invoices to confirm the zero rating those sales relied on actually holds up.
Form 211 Preparation
Completing the disclosure with the original figures, corrected figures, and the date each error was discovered.
Background Letter and Supporting Documentation
Writing the explanation the FTA expects and assembling the invoices and records that substantiate the corrected numbers.
EmaraTax Submission and Payment Guidance
Filing within the 20 business day window and confirming the fixed and percentage-based penalties owed alongside the disclosure.
Corrections Built for How Sharjah Businesses Actually Trade
Ahmed Mahfoudh Chartered Accountants & Auditors starts a disclosure by checking the errors specific to Sharjah's trading and import activity, reverse charge on services bought from abroad, zero-rated exports missing their proof of removal, supplies coded to the wrong category. Every error found in a period is consolidated into one Form 211, since only one disclosure is accepted per period. For a Sharjah business, that's what keeps a correction from becoming two filings and two fixed penalties instead of one.
Where Sharjah Disclosures Usually Get Missed
The errors that need disclosing are rarely in the obvious places, they're in reverse charge and export paperwork nobody reviews line by line.
We Check Reverse Charge on Imports First
Reverse charge is self-assessing, so nothing on an invoice flags it as missing. We test imported services specifically, since this is one of the first things an FTA review looks for in a trading business.
Every Error in a Period Goes Into One Filing
A second disclosure for the same period isn't accepted the same way a first one is, and a repeat disclosure carries the AED 5,000 fixed penalty instead of AED 3,000. We review the whole period before filing anything.
Zero-Rated and Exempt Supplies Get Separated Properly
The two categories affect your recovery ratio differently, and a mix-up here doesn't correct itself, it repeats until someone catches it. We check this classification specifically rather than assuming it was set up correctly once and left alone.
Export Proof Gets Verified, Not Assumed
We match the customs declaration and shipping documents against the export invoice before relying on the zero rating in a disclosure, since a gap here is what converts an export sale into a taxable one.
We Stay on the File Until the FTA Confirms It
If a query comes back on the figures or the explanation, we respond directly instead of leaving you to interpret an EmaraTax notification alone.
Who Prepares Your Disclosure
Accountants who review the error, write the disclosure, and file it directly with the FTA.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
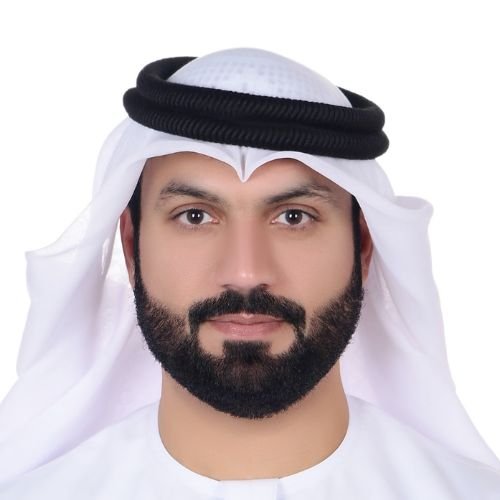
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
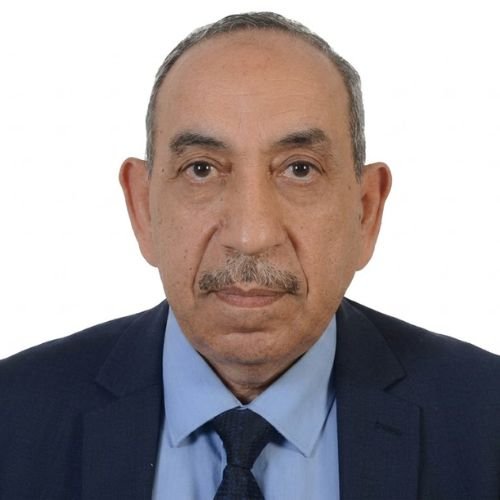
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
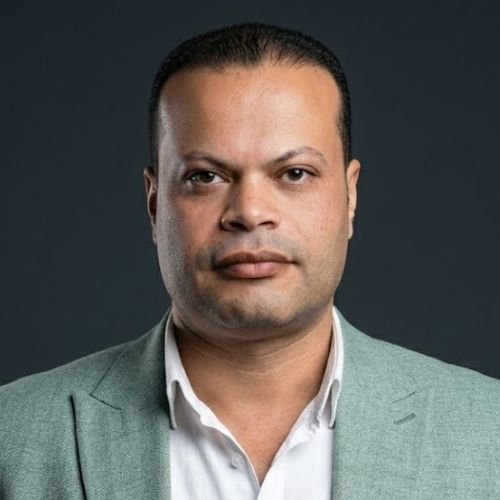
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Sharjah Finance Teams Say
Feedback from trading and distribution businesses we've guided through correcting past VAT errors.
“Their VAT voluntary disclosure service helped us correct past errors properly and minimise potential penalties. The disclosure was accepted by the FTA without further issues.”
“I was worried about previous VAT mistakes until this team guided me through voluntary disclosure. The process felt controlled and the outcome was positive.”
“Professional handling of a sensitive VAT voluntary disclosure. The analysis was thorough and the disclosure was submitted correctly.”
“Facing the need for voluntary disclosure created real stress. Errors were identified, corrected, and disclosed properly with clear communication throughout.”
“Practical help reviewing past returns and preparing a complete voluntary disclosure. Our exposure to penalties was reduced and our VAT position brought back into compliance.”
“Precise, discreet, and dependable. The entire process was handled with care and delivered a clean resolution.”
Voluntary Disclosure Questions
What Sharjah businesses ask before correcting a past VAT error.
Do I need to file a Form 211 for every error?
Only if the error affects tax due by more than AED 10,000. Errors of AED 10,000 or less can usually be corrected on your next VAT return instead.
Can I file more than one disclosure for the same period?
No, only one disclosure is accepted per tax period. If a second error from that period surfaces later, it needs combining into the existing correction rather than filed separately.
Why does reverse charge on imports come up so often for Sharjah traders?
It's self-assessed, meaning there's no supplier invoice flagging it as missing. That makes it one of the most commonly omitted VAT items and an early point of focus in an FTA review.
What happens if a zero-rated export is missing its shipping proof?
Without matching customs and commercial evidence, the sale can be treated as standard-rated rather than zero-rated, which changes the tax due for that period.
How quickly do I need to disclose an error?
Within 20 business days of discovering it, if the error exceeds the AED 10,000 threshold.
What penalty applies to a voluntary disclosure?
A fixed AED 3,000 for a first disclosure, AED 5,000 for a repeat one, plus a percentage of the unpaid tax that rises from 5% in year one up to 40% after year four.
What happens if the FTA finds the error before I disclose it?
It's treated more strictly than a voluntary disclosure, since correcting it yourself before the FTA discovers it independently is what keeps the lower penalty tier available.
What documents does a disclosure need?
A background letter explaining the error, the original and corrected calculations, and the invoices, customs records, or contracts that support the correction.
Still have questions? We're here to help.
Call Us Now