VAT Registration Services
in Dubai
We establish whether and when you must register, prepare the turnover evidence, submit the EmaraTax application and respond to FTA queries until a decision is issued.
13+ YEARS OF UAE TAX AND AUDIT EXPERIENCE
- Threshold Assessment
- EmaraTax Submission
- TRN Review
Register From the Correct Date
The application must explain when the threshold was crossed and prove the figures behind that conclusion.
Correct Registration Basis
Taxable turnover is separated from exempt and outside-scope income before mandatory or voluntary eligibility is selected.
Defensible Effective Date
Monthly revenue evidence shows when the registration obligation arose instead of relying on the application submission date.
Fewer FTA Queries
Consistent declarations, licences, contracts and invoices reduce avoidable questions caused by conflicting application figures.
Proper TRN Structure
Branches, sole establishments and related entities are assessed before separate registration or VAT grouping is requested.
Ready First Return
The handover identifies the first tax period, effective date and transactions requiring VAT treatment after registration.
Visible Deadline Risk
Businesses that crossed the threshold late receive a dated exposure assessment before the application is submitted.
What Enters the FTA Application
Every application is built around legal identity, taxable activity, turnover evidence and the requested registration date.
Eligibility Assessment
Determine whether mandatory, voluntary, non-resident or exception rules apply.
Turnover Calculation
Build a monthly schedule of taxable supplies and imports for twelve months.
Forecast Threshold Test
Examine signed contracts and orders supporting expected turnover within thirty days.
Effective Date Review
Identify when the legal registration obligation or voluntary eligibility first arose.
Document File Preparation
Organise licences, incorporation records, identification, authority documents and business evidence.
EmaraTax Application
Complete the taxable-person profile and prepare the VAT registration submission.
VAT Group Registration
Assess related-party conditions and prepare member declarations and group supporting records.
FTA Query Response
Reconcile additional information requests with the original turnover schedule and documents.
TRN Handover
Check the certificate, effective date, tax periods and registered entity details.
FTA Registration Specialists
Ahmed Mahfoudh Chartered Accountants & Auditors has more than 13 years of UAE tax, accounting and audit experience. Our Dubai practice includes FTA-registered tax agents who prepare VAT applications from the supporting records upward. We classify revenue, establish the threshold date and align EmaraTax entries with licences, incorporation documents, invoices and contracts. The work continues through FTA information requests and ends with a checked registration certificate, effective date and first-period compliance handover.
The Threshold Needs Supporting Evidence
Many applicants enter annual revenue without separating taxable supplies or proving the month registration became compulsory.
Revenue Is Classified Before Counting
We separate standard-rated, zero-rated, exempt and outside-scope amounts before calculating turnover. This matters because zero-rated supplies normally count toward the registration threshold, while exempt and outside-scope income generally do not.
Twelve Months Means a Rolling Test
Mandatory registration is not decided only from the last financial year. We prepare a month-by-month schedule covering the preceding 12 months, identify the first threshold-crossing date and retain the underlying invoices or revenue reports.
Forecasts Need Commercial Evidence
The next-30-day test cannot rest on an unsupported sales estimate. Expected taxable supplies are connected to signed contracts, purchase orders or other credible documents showing why management reasonably expected the AED 375,000 threshold to be exceeded.
The Effective Date Is Reconstructed
The requested effective date is checked against the historical or expected turnover test. If the application is late, we show when the obligation arose and identify the periods that may require VAT accounting after registration.
Legal Identity Controls the Documents
A limited liability company, sole establishment, partnership, charity and non-resident business require different identity and authority evidence. We match the uploaded documents to the selected EmaraTax legal-person or natural-person profile.
Sole Establishments Are Combined
All sole establishments owned by the same natural person are registered under one TRN. Their activities are combined when testing the VAT threshold, preventing separate trade licences from being incorrectly treated as separate taxable persons.
Branches Stay With the Parent
UAE branches of the same legal entity do not receive separate VAT registrations. The parent company receives one TRN, includes its branches in the application and later files one VAT return covering them.
Application Figures Stay Consistent
The taxable-supplies table, turnover declaration and supporting schedules must agree. We check names, licence numbers, monthly values, registration dates and uploaded evidence before submission because small contradictions often trigger additional FTA questions.
Registration Ends With a Handover
Once approved, we verify the TRN, effective date and assigned tax periods. Management also receives the registration certificate and a starting checklist covering tax invoices, accounting codes, opening transactions and the first VAT return.
Specialists in FTA Applications
Tax agents and accountants connect each EmaraTax answer to the company’s legal and financial evidence.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
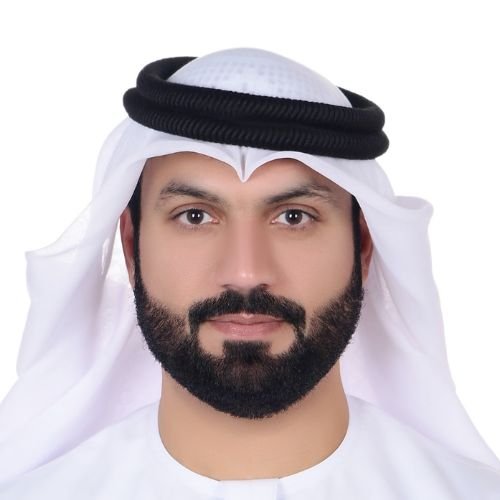
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
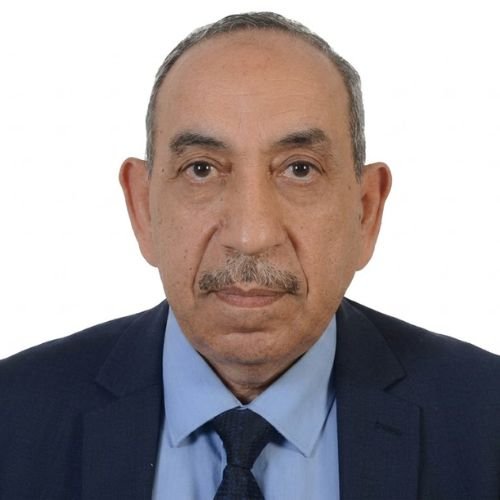
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
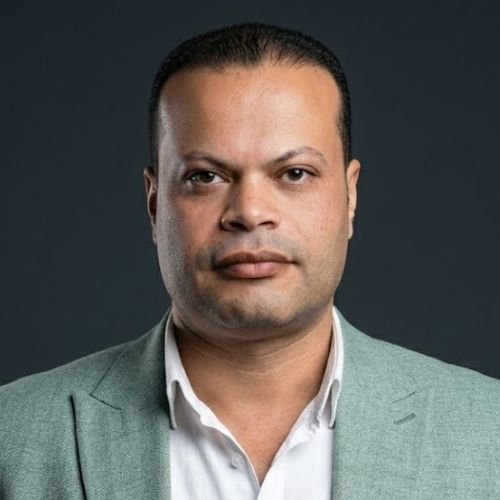
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Newly Registered Businesses Say
These owners and finance managers needed the right TRN, effective date and supporting documents accepted by the FTA.
“Our VAT registration was completed without errors. The documents were handled correctly, and our TRN was issued on schedule.”
“Clear guidance made registration straightforward. Eligibility checks, document preparation and submission were managed efficiently.”
“They ensured every registration detail met FTA requirements and helped us avoid the common delays businesses face.”
“Structured support made VAT registration simple and transparent, from preparing the application through receiving approval.”
“Documentation and FTA follow-up were handled accurately. We received our TRN without any issues.”
“Their VAT registration assistance provided clear steps, timely updates and a successful outcome.”
VAT Registration Rules Explained
These are the questions that determine whether you apply, when registration starts and what evidence the FTA expects.
Who must register for UAE VAT?
A UAE-resident business must register when taxable supplies and imports exceed AED 375,000 during the previous 12 months or are expected to exceed that amount within 30 days.
What is the voluntary registration threshold?
A UAE-resident business may apply voluntarily when taxable supplies, imports or taxable expenses exceed AED 187,500 during the previous 12 months or are expected to exceed it within 30 days.
How long do I have to apply?
A person required to register must submit the VAT registration application within 30 days of the registration obligation arising.
What counts toward the mandatory threshold?
The calculation generally includes standard-rated and zero-rated supplies plus relevant imports. Exempt and outside-scope amounts are treated separately.
Do zero-rated sales count?
Yes. A zero-rated supply remains a taxable supply even though VAT applies at 0%, so it generally counts toward the registration threshold.
Do exempt sales count?
Exempt supplies generally do not count toward the taxable-turnover threshold. They must still be identified correctly because exempt and zero-rated treatments produce different registration outcomes.
Does one capital asset sale count?
A one-off disposal of a capital asset is generally excluded when calculating taxable supplies for the registration threshold. The transaction must genuinely be a capital asset disposal.
How is the 12-month test calculated?
It is a rolling test, not only a calendar-year or financial-year calculation. Taxable supplies and imports are reviewed month by month over the preceding 12 months.
What is the next-30-day test?
Registration becomes mandatory when the business reasonably expects taxable supplies and imports to exceed AED 375,000 during the coming 30 days. Contracts or purchase orders should support that expectation.
Can a new company register?
Yes, if it satisfies the mandatory or voluntary test. A new business may rely on expected revenue supported by signed contracts, purchase orders or other valid commercial evidence.
Can expenses support voluntary registration?
Yes. Taxable expenses exceeding AED 187,500 in the previous 12 months or expected next 30 days may support voluntary registration, subject to adequate evidence.
What evidence is needed for expenses?
The FTA service requirements state that expense-based applications should include at least five VAT invoices with amounts exceeding the voluntary registration threshold.
Do foreign businesses use AED 375,000?
No. The mandatory threshold does not apply to a non-resident making taxable UAE supplies where no other UAE person is responsible for accounting for the tax.
Can someone without a licence register?
Registration provisions may apply to a natural or legal person conducting an economic activity even without a trade licence. Other evidence must establish the activity and identity.
Must a free-zone company register?
Free-zone status does not automatically remove VAT registration obligations. The company must test its supplies and imports against the same mandatory or voluntary conditions.
Are designated zones outside UAE VAT?
No. Designated-zone treatment depends on the transaction and prescribed conditions. The FTA may request a business-flow explanation, movement-of-goods evidence and supply-chain records.
Do branches need separate TRNs?
No. Branches of the same legal entity are included under one VAT registration, receive one TRN and submit one return through the parent entity.
Still have questions? We're here to help.
Call Us Now