FTA Audit Assistance
in Dubai
We organise the response to an FTA audit, reconcile filed tax positions and prepare evidence that answers the authority’s requests without contradictions or unsupported explanations.
13+ YEARS OF UAE TAX AND AUDIT EXPERIENCE
- VAT Audit Support
- Corporate Tax Support
- EmaraTax Coordination
Keep the Audit Controlled
Every deadline, document and explanation is managed against the tax return the FTA is examining.
Deadline Control
A dated response register keeps authority requests, responsible staff, supporting documents and submission deadlines visible throughout the audit.
Consistent Evidence
Returns, ledgers, invoices and explanations are reconciled before submission, reducing contradictions that could lead to further questions.
Clear Tax Positions
Management sees which treatments are supported by legislation, which require stronger evidence and which may need correction.
Earlier Exposure View
Potential tax differences are quantified before formal responses are sent, allowing informed decisions about disclosure, defence or professional legal input.
Preserved Review Rights
Audit results and assessment dates are recorded immediately, helping the business protect the statutory deadlines available for challenging an FTA decision.
Managing the FTA Examination
Support begins with the notice and continues through document requests, meetings, findings and any resulting assessment.
Audit Notice Assessment
Identify covered taxes, periods, locations, deadlines, requests and authorised contacts.
Pre-Audit Exposure Review
Reconcile filed positions and assess whether identified errors require voluntary disclosure.
VAT Audit File
Test VAT returns against sales, purchases, imports, invoices and ledger balances.
Corporate Tax Audit File
Rebuild taxable income from financial statements, adjustments, elections, reliefs and schedules.
Transfer Pricing Support
Organise related-party records, pricing support, agreements and required disclosure schedules.
Evidence Pack Preparation
Index requested records and connect each response to verifiable supporting documents.
FTA Response Management
Draft factual replies, control versions and track every submission and follow-up query.
Audit Meeting Assistance
Prepare company representatives and support authority meetings or business-premises inspections.
Post-Audit Decision Review
Analyse assessments, penalties, calculation differences and available statutory review routes.
Tax Support Under FTA Review
Ahmed Mahfoudh Chartered Accountants & Auditors combines more than 13 years of UAE tax and audit experience with FTA-registered tax support. Our Dubai team connects VAT and Corporate Tax returns to accounting records, invoices, contracts and transaction evidence before anything is submitted. We assist with document preparation, technical explanations, authority queries and post-audit findings. Where formal representation is required, the responsible registered tax agent or legal representative is identified and authorised through the proper channel.
One Response Record From Day One
The usual mistake is answering each FTA query separately without reconciling it to earlier replies, filed returns and accounting records.
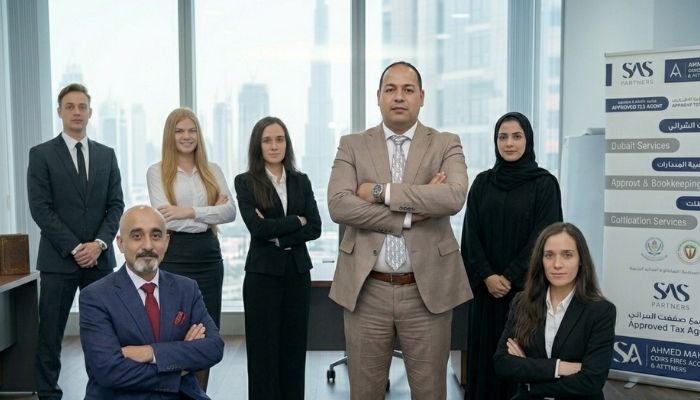
The Notice Becomes a Control Sheet
The audit notice is broken into taxes, periods, entities, requested records and response dates. Each item receives an owner and status, while every submission is retained with its final attachments and transmission evidence.
Filed Returns Anchor the Review
We begin with what the business actually reported to the FTA. VAT or Corporate Tax returns are matched to trial balances, tax ledgers and filed schedules before explanations are prepared, exposing differences between accounting data and submitted positions early.
VAT and Corporate Tax Stay Distinct
VAT testing follows supplies, tax points, invoices, input recovery, imports and adjustments. Corporate Tax testing starts with accounting income and follows tax adjustments, exemptions, reliefs and related-party positions. Evidence is organised according to the tax being examined.
Each Reply Answers One Request
Responses identify the transaction, tax treatment, calculation and supporting evidence relevant to the FTA’s question. Extra commentary that creates new ambiguity is removed, but material facts are never withheld or replaced with assumptions.
Weak Positions Are Quantified Early
If a treatment lacks support, we calculate the possible tax difference and explain the technical and documentary weakness to management. That allows the business to decide its response before an unsupported position is repeated in writing or during a meeting.
Disclosure Timing Is Assessed Immediately
An error may require voluntary disclosure, but an audit notice can affect the available procedure and penalty outcome. We establish when the error was discovered, whether it exceeds the relevant correction rules and whether the FTA has already opened an examination.
Meetings Use the Same Facts
Company representatives receive a briefing on the audit scope, submitted records and unresolved questions. A meeting note records requests, explanations and agreed follow-up items, reducing the risk of different departments giving conflicting accounts of the same transaction.
Assessment Dates Trigger the Next Step
Once an assessment or penalty decision arrives, the notification date, disputed amounts and legal deadlines are recorded. Technical review, reconsideration, committee objection or legal referral is then considered under the route available for that specific decision.
Tax Professionals During FTA Review
Accountants rebuild the records while tax specialists assess treatments, disclosures and authority responses.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
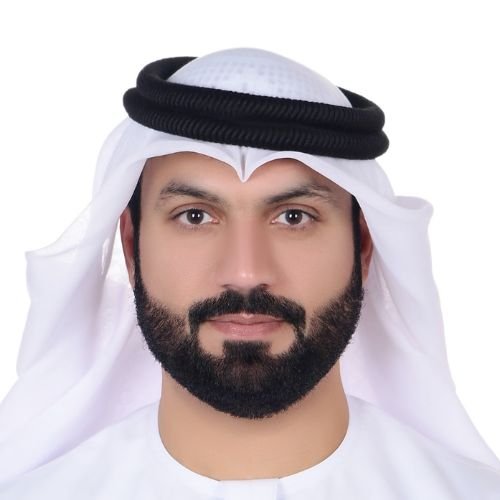
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
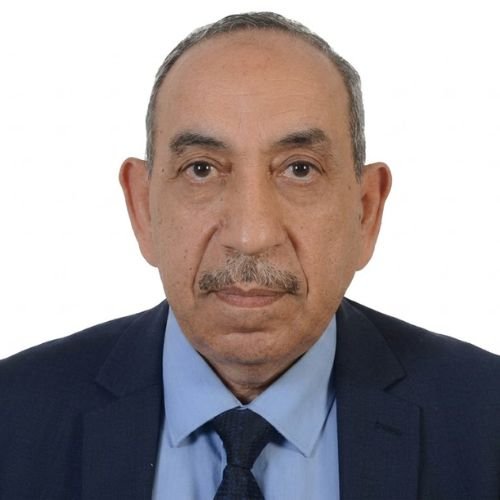
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
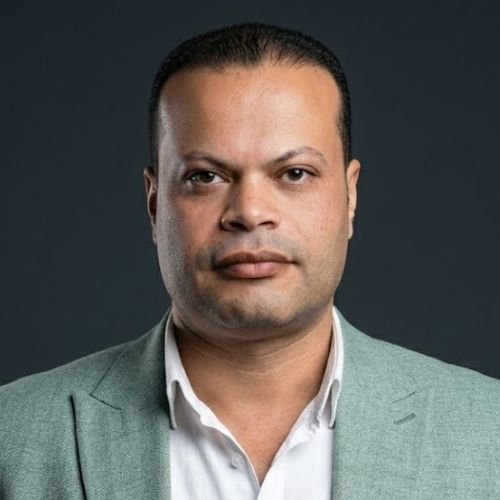
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Dubai Tax Teams Say
These finance leaders and business owners have managed document requests, technical questions and deadlines during FTA examinations.
“They kept the FTA audit under control. Documents were organised, responses were timely, and we avoided unnecessary complications with the authority.”
“Their preparation identified risk areas early and structured our records properly, which made a clear difference during the FTA review.”
“They understood the authority’s requirements and helped us present accurate information without delays or confusion throughout the audit.”
“Their structured support made a stressful FTA audit manageable. Queries were handled efficiently, and the outcome clarified our tax positions.”
“Their practical help with document retrieval and transaction explanations reduced our penalty exposure and clarified the FTA’s compliance expectations.”
“Reliable, knowledgeable and calm under pressure. Their assistance gave us the support required at every stage of the FTA audit.”
Responding to an FTA Audit
These are the rules, records and deadlines businesses need to understand once the authority begins its review.
What is an FTA tax audit?
It is an examination performed by the Federal Tax Authority to verify compliance with UAE tax legislation. The FTA may audit commercial records, information, data, goods and filed tax positions.
Can the FTA audit any business?
The Tax Procedures Law allows the FTA to audit any person to verify compliance with the law. An audit is not limited to businesses above the VAT registration threshold.
How much notice does the FTA give?
The FTA generally provides at least 10 business days’ notice before conducting a tax audit. The Tax Procedures Law permits exceptions where specified legal conditions are met.
Can an audit happen without notice?
Yes, in specified cases involving suspected tax evasion, obstruction or similar grounds. The law permits temporary closure of the relevant place for up to 72 hours under the prescribed authorisation process.
Where can the audit take place?
The FTA may conduct the audit at its premises, the taxpayer’s business premises or another location where business is conducted, goods are stored or records are kept.
Which taxes can be examined?
An FTA audit may cover VAT, Corporate Tax or Excise Tax, depending on the notice. The audited tax types and periods should be confirmed before records are assembled.
Does AED 375,000 prevent an audit?
No. AED 375,000 is relevant to the Corporate Tax rate and mandatory VAT registration rules in different ways; it is not an FTA audit-exemption threshold.
What should we do first?
Record the notification date, tax type, periods, requested records and response deadline. Access to the relevant EmaraTax profile and filed returns should also be secured immediately.
Who may speak to the FTA?
The taxpayer may respond directly or act through an authorised legal representative or FTA-registered tax agent. Formal portal access and appointment requirements must be completed where representation is involved.
Can our accountant represent us?
An accountant can prepare reconciliations and evidence. Formal tax representation requires the person to hold the appropriate authority, such as appointment as a registered tax agent or legal representative.
What VAT records are usually requested?
Records may include sales and purchase invoices, credit notes, import documents, reverse-charge calculations, VAT ledgers, return workings, bank records and contracts supporting the nature of supplies.
What Corporate Tax records are required?
The FTA may review financial statements, ledgers, tax-return workings, elections, reliefs, related-party schedules, transfer pricing evidence and documents supporting exempt or qualifying income.
How long are Corporate Tax records retained?
Taxable Persons and Exempt Persons must retain relevant Corporate Tax records for at least seven years after the end of the related Tax Period.
How long are VAT records retained?
VAT records are generally retained for at least five years after the relevant Tax Period. Records relating to real estate must be retained for 15 years.
Can the FTA inspect original documents?
Yes. A taxpayer has the right to obtain copies of original paper or digital documents taken or obtained by the FTA during the audit, subject to the applicable procedures.
Can we ask for auditor identification?
Yes. The person being audited may request the tax auditor’s official identification card and obtain a copy of the tax audit notification.
May management attend the audit?
The taxpayer has the right to attend an audit conducted outside the FTA’s premises. Relevant finance, tax and system personnel should be identified before the meeting.
Can the FTA access accounting systems?
The authority may examine digital records relevant to the audit. Access should be controlled, documented and limited to the systems and information lawfully requested.
Must records be submitted in Arabic?
The FTA may request an Arabic translation of records provided in another language. The required translation format and submission deadline should be confirmed from the authority’s request.
Still have questions? We're here to help.
Call Us Now