Internal Audit Services
in Dubai, UAE
We test how controls work in practice, document the gaps, rank each finding by risk and verify whether agreed corrective actions are completed.
13+ YEARS OF UAE AUDIT EXPERIENCE
- DDA Approved
- Risk Based
- Action Tracked
See Where Controls Fail
Policies may look correct on paper while approvals, access rights and daily workarounds leave the business exposed.
Board Visibility
Directors receive an independent view of control performance instead of relying entirely on the departments responsible for those controls.
Prioritised Exposure
Findings are ranked by impact and likelihood, helping management address serious financial, operational and compliance risks first.
Clear Accountability
Every agreed action has an owner and target date, making unresolved weaknesses visible during follow-up reviews.
Reduced Fraud Opportunity
Reviews expose incompatible duties, weak approvals and excessive system access that could allow errors or deliberate misuse to continue.
Fewer Repeat Findings
Corrective actions are retested after implementation, so closed findings represent working controls rather than completed paperwork.
Internal Audit Workstreams
Choose full outsourcing, support for your existing function or a focused review of one high-risk process.
Audit Function Outsourcing
Operating the internal audit programme from risk assessment through reporting and follow-up.
Co-Sourced Audit Support
Providing additional auditors or specialist skills for your existing internal audit function.
Risk-Based Audit Planning
Mapping auditable areas, evaluating exposure and preparing a prioritised annual audit plan.
Operational Process Audits
Testing procurement, sales, inventory, payroll, logistics and other day-to-day operating controls.
Financial Control Reviews
Examining approvals, reconciliations, journal entries, payment controls and financial reporting processes.
Compliance Control Testing
Checking whether regulated activities and internal procedures follow applicable UAE requirements.
IT Control Reviews
Reviewing user access, change management, backups, system administration and technology-dependent controls.
Fraud Risk Reviews
Assessing segregation of duties, management override, conflicts of interest and asset misuse risks.
Follow-Up Validation
Retesting completed actions and reporting findings that remain unresolved or ineffective.
Dubai Control Review Experience
Ahmed Mahfoudh Chartered Accountants & Auditors brings more than 13 years of UAE audit experience to internal control reviews. The firm operates from Dubai and is approved by the Dubai Development Authority. Assignments can draw on audit, tax and legal managers when a finding crosses disciplines. Work is built around risk assessment, evidence testing, documented findings, management responses and follow-up. This gives boards and business owners a usable record of what failed, why it matters and who must correct it.
Findings That Survive Scrutiny
The biggest mistake is accepting written procedures as proof that controls work during real transactions.
We Test Actual Control Performance
Interviews explain how a process is supposed to work. Evidence shows what happened. We inspect selected transactions, approvals, reconciliations, access rights and supporting records before deciding whether a control exists, operates consistently or has been bypassed.
Every Finding Shows Its Basis
Reports connect each finding to the condition observed, the expected control, the underlying cause and the resulting exposure. Recommendations are linked to that evidence, giving management enough detail to correct the weakness without guessing what the auditor meant.
Risk Ratings Drive the Discussion
A missing signature and unrestricted payment access shouldn’t receive equal attention. Findings are graded using agreed impact and likelihood criteria, then discussed with process owners before final reporting so decision-makers can focus on material exposure.
Management Responses Stay on Record
Process owners can correct factual inaccuracies, explain constraints or disagree with a recommendation. Their response, action owner and target date are recorded alongside the finding. Independence is preserved because disagreement doesn’t automatically remove a supported audit observation.
Follow-Up Requires Working Evidence
An action isn’t closed because someone says it is complete. We inspect the revised procedure, system configuration, approval record or transaction sample needed to confirm that the new control has been implemented and is operating as intended.
Serious Matters Are Escalated
Suspected fraud, regulatory breaches or control failures with material exposure follow the agreed reporting route. Relevant evidence is preserved, access is limited and management is told when the issue requires legal, forensic, tax or regulatory input.
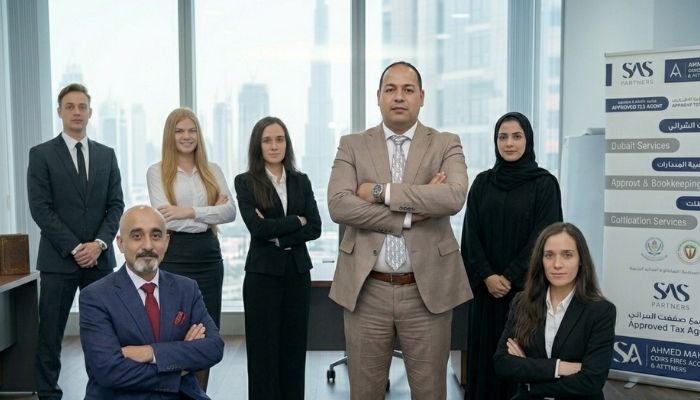
Auditors Testing Your Controls
Audit, tax and legal specialists contribute when a control failure extends beyond one business function.
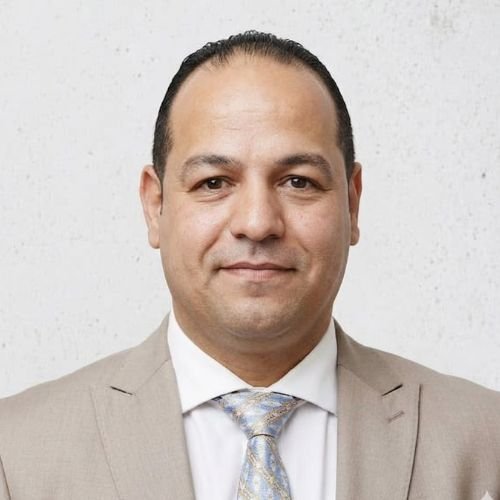
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Dubai Decision-Makers Found
These leaders used internal audit to examine controls, uncover overlooked risks and make corrective action manageable.
“Their internal audit identified control gaps we had overlooked for months. Findings were clear, prioritised and supported by practical recommendations that strengthened processes across key departments.”
“Their objective review of procurement and payment controls highlighted real risks and gave us a structured plan to address them. Valuable and professional throughout.”
“Independent internal audit support that strengthened governance without unnecessary disruption. Reports were balanced, evidence-based and focused on operational efficiency as well as control.”
“They examined our policies and daily practices carefully, then delivered constructive, actionable findings. Their collaborative yet independent approach improved our overall control environment.”
“Their review exposed process weaknesses and fraud risks. The recommendations helped us tighten segregation of duties and improve documentation beyond a standard review.”
“Their well-organised review provided independent assurance over key controls and realistic improvement steps. They’re a reliable choice for ongoing governance needs in Dubai.”
Before Commissioning an Internal Audit
Understand the scope, reporting line, timing and responsibilities before auditors begin testing your controls.
Is internal audit mandatory in the UAE?
It isn’t universally mandatory for every UAE company. CBUAE rules require banks to maintain an internal audit function, while DFSA Authorised Firms must establish one unless an applicable waiver is obtained.
Which internal audit standards apply?
The IIA Global Internal Audit Standards became effective on 9 January 2025. They cover independence, board oversight, engagement planning, evidence, reporting and monitoring action plans.
How often should internal audits occur?
Frequency follows the organisation’s risk assessment and approved audit plan. Critical processes may be reviewed quarterly, while stable lower-risk areas may remain on an annual or rotating cycle.
How long does an internal audit take?
Timing is set after confirming the processes, locations, systems, sample sizes and available records. The agreed plan separates document collection, fieldwork, draft findings, management responses and final reporting.
How much do internal audit services cost?
Fees are based on scope, business locations, process complexity, specialist testing and reporting frequency. A single-process review is priced separately from an annual outsourced internal audit programme.
What documents will auditors request?
Requests usually include policies, organisation charts, authority matrices, system-access lists, contracts, reconciliations, transaction records and earlier audit reports. The final request list follows the approved engagement scope.
Do auditors examine every transaction?
Usually not. Internal audit applies risk-based sampling unless the engagement specifically requires full-population testing or data analysis across every transaction.
Can internal audit guarantee fraud detection?
No internal audit provides an absolute guarantee that every fraud will be found. It evaluates fraud exposure and control design; suspected misconduct may require a separately scoped forensic investigation.
What happens when management disputes a finding?
Management can provide additional evidence or a written response before the report is finalised. A supported finding remains reportable even when the process owner disagrees with its rating or recommendation.
Who receives the internal audit report?
The reporting route is agreed before fieldwork and should protect the function’s independence. Regulated entities may require direct accountability to the board or audit committee rather than the manager responsible for the reviewed process.
What happens after findings are reported?
Each accepted action is assigned an owner and target date. Follow-up testing checks whether the promised control was implemented and works before the finding is treated as closed.
Is internal audit different from external audit?
Yes. External audit provides an opinion on financial statements for a defined reporting period; internal audit examines governance, risk management and controls across financial, operational, compliance and technology processes.
Can you support our existing audit team?
Yes. A co-sourced arrangement adds auditors or specialist knowledge while the company retains its internal audit leadership, approved plan and reporting relationship.
Can reviews be conducted remotely?
Document review and interviews can be completed remotely where secure access is available. Physical inventory, site security and controls requiring direct observation need scheduled on-site testing.
Still have questions? We're here to help.
Call Us Now