Auditing Services
in Dubai
Nobody hires an auditor because they want to. You hire one because your free zone authority demands it, your bank will not renew without it, or the corporate tax law now requires it. The question is whether the firm you appoint finds the problems before your regulator does.
DMCC APPROVED AUDITORS LIST | UAE MINISTRY OF ECONOMY
- External Audit
- Assurance Services
- Management Letter
The Audit Your Stakeholders Actually Read
Your bank skips to the opinion paragraph. Your free zone authority checks the summary sheet. Your investor reads the disclosures. Each one is looking for a reason to trust -- or not.
Problems Found During Fieldwork, Not After Filing
A misstatement discovered by the auditor during the engagement is an adjustment. The same misstatement discovered by the FTA after submission is a dispute. We test hard so you correct early.
The Right Licence for Your Authority
DMCC accepts opinions only from its Approved Auditors List. DIFC requires DFSA-registered or DIFC-licensed auditors. A report signed by the wrong firm is rejected at the portal regardless of quality.
A Management Letter Worth Reading
We document what we observed, what it exposes, and what to change -- sized to your operations. Not fourteen pages of boilerplate copied from last year's file.
Fieldwork Planned Around Your Calendar
We do not arrive when we are available. We arrive when your records are ready and your deadline is approaching. The engagement timeline is agreed during planning and honoured during execution.
Every Examination We Conduct and Why It Matters
An audit is a sequence of tests designed to answer one question -- are these financial statements materially correct?
External Statutory Audit
Independent examination of annual financial statements under ISA, concluding with a signed opinion on whether the statements present a true and fair view.
DMCC Compliance Audit
Audit for DMCC-registered entities with portal-ready deliverables -- signed financial statements, auditor's report, and summary sheet formatted for the Member Portal submission within the 180-day window.
DIFC & ADGM Audit
Full IFRS audit required by financial centre authorities within four months of year-end. No IFRS for SMEs accepted. Auditor must hold appropriate regulatory registration.
JAFZA & DAFZA Audit
Audit packaged to the specific format and portal requirements of each industrial free zone, with separate tracking of submission deadlines and authority-specific documentation.
Corporate Tax Audit Support
Audited statements meeting Ministerial Decision No. 84 of 2025 -- mandatory for entities exceeding AED 50 million revenue, all tax groups, and qualifying free zone persons claiming the 0% rate.
Consolidated Group Audit
Multi-entity examination covering parent and subsidiary balances, intercompany elimination verification, segment reporting, and minority interest adjustments across jurisdictions.
Revenue Recognition Testing
Contract-by-contract review against IFRS 15 criteria -- performance obligations identified, transaction price verified, and timing of recognition tested against delivery evidence.
Inventory Count Attendance
Physical presence at your warehouse or site during stock count, with test counts, condition assessment, and valuation cross-check against recorded figures.
Bank & Third-Party Confirmations
Direct confirmation of bank balances, receivable balances, and payable balances with counterparties to verify the existence and accuracy of reported financial positions.
Internal Controls Evaluation
Assessment of authorisation procedures, access restrictions, reconciliation practices, and segregation of duties -- weaknesses reported with specific remediation steps in the management letter.
Related-Party Disclosure Testing
Completeness and arm's length testing of transactions between connected persons, owners, and affiliated entities -- a primary focus area for the FTA under corporate tax transfer pricing rules.
We Sign Opinions We Are Accountable For
Ahmed Mahfoudh Chartered Accountants & Auditors holds an active audit licence from the UAE Ministry of Economy and appears on the DMCC Approved Auditors List. Those registrations are not marketing credentials -- they are regulatory permissions that carry personal and professional liability every time we sign an opinion. We conduct statutory audits for trading companies, manufacturers, service firms, and holding structures across mainland and free zone jurisdictions. Every engagement follows International Standards on Auditing from risk assessment through substantive procedures to the final report. When we sign, we are telling your bank, your regulator, and the FTA that we tested the numbers and stand behind the conclusion.
Why Companies Get the Wrong Audit
The cheapest audit is the one that misses something. You pay for that later -- at the bank, at the FTA, or in front of your investors.
An Audit Is Not an Accounting Service
Some firms prepare your books all year and then sign the audit opinion on the same set of numbers. That is not an audit -- it is self-review. International Standards on Auditing require the examiner to be independent of the records being examined. We do not blur the line. If we audit your company, another firm keeps your books. If we keep your books, another firm audits them. The opinion only carries weight when the person signing it had no role in producing the numbers.
Your Auditor Should Cost You Less Next Year
A well-run first audit creates a permanent file -- documented risks, tested controls, prior-year adjustments, and a mapped chart of accounts. Year two starts from that file, not from scratch. If your audit fee keeps climbing, either the scope is growing or the prior firm did not build a proper working file. We invest in year one so the engagement becomes more efficient, not more expensive, over time.
A Qualified Opinion Is Not a Technicality
Banks read the auditor's opinion before they read the balance sheet. A qualified opinion means the auditor found a material departure from accounting standards or could not verify a material balance. That one paragraph changes how lenders price your facility, how investors assess your credibility, and how regulators prioritise their reviews. We identify qualification risks during planning and resolve them during fieldwork -- not after the draft report is circulated.
The FTA Now Cross-Checks Your Audit
Under Ministerial Decision No. 84 of 2025, companies with revenue above AED 50 million, all tax groups, and qualifying free zone persons must file audited financial statements with their corporate tax return. The taxable income computation starts from the audited profit figure. If the audit adjustments are sloppy or the statements do not tie to the return, the FTA has grounds to open a review. Your audit is no longer just for your free zone portal -- it feeds directly into your tax position.
Every Free Zone Has Its Own Audit Rules
DMCC requires a signed summary sheet that reconciles exactly to the audited figures, submitted through the Member Portal within 180 days. DIFC demands full IFRS with no simplified framework permitted, and the auditor must be registered with the DFSA or hold a DIFC licence. JAFZA has a separate portal with different formatting. A firm that treats all free zone audits the same will produce a submission that gets returned. We format every deliverable for the specific authority that receives it.
The Management Letter Is Where You Get Value Beyond Compliance
The audit opinion tells you whether your statements are materially correct. The management letter tells you what is about to go wrong if you do not fix it. We report control gaps we observed during testing -- an approval workflow with no segregation, a bank account nobody reconciles, a receivable balance that has been outstanding for nine months with no provision. Each finding includes the exposure amount and a recommendation that matches your company's size, not a textbook control framework.
The Auditors Who Examine Your Records
Licensed professionals who test transactions, verify balances, and sign opinions under their own name.
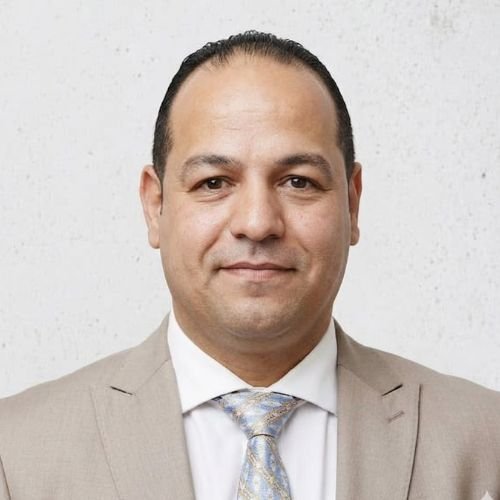
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
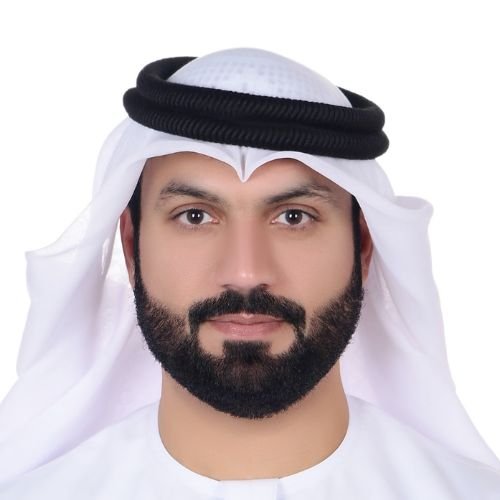
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
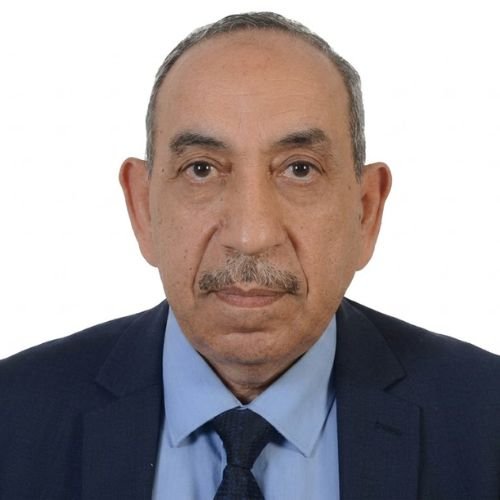
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
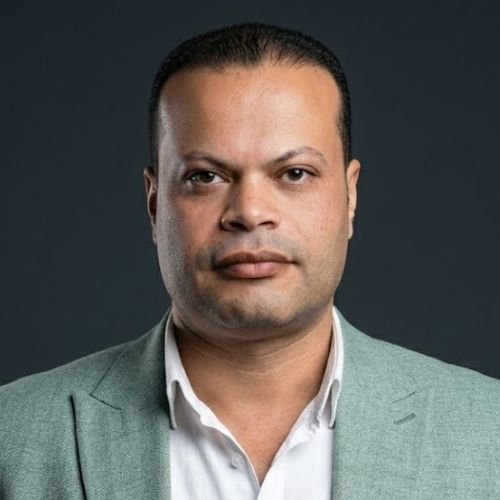
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
Directors and Controllers on Their Audit
Companies across Dubai that chose an auditor for rigour, not for convenience.
“Thorough external audit completed on schedule. The team identified key improvement areas while maintaining full professional independence.”
“Well organised from planning to final report. Communication stayed clear and disruption to daily operations remained minimal.”
“Independent assurance that strengthens our standing with banks and shareholders. Strong technical knowledge and a report meeting all regulatory expectations.”
“Questions were relevant, findings explained clearly, and the final report arrived without unnecessary delays. A professional experience.”
“Their recommendations helped us tighten internal controls and improve documentation. The audit added real operational value beyond compliance.”
“Reliable, precise, and fully independent. Met every deadline and produced a clear, credible report.”
Choosing an Auditor in Dubai
What directors and finance heads need to know before appointing a firm to examine their financial statements.
Who is legally required to have an audit in the UAE?
Three categories under Ministerial Decision No. 84 of 2025 -- companies with revenue exceeding AED 50 million, every tax group regardless of size, and qualifying free zone persons claiming the 0% corporate tax rate. Beyond that, DMCC, JAFZA, DAFZA, DIFC, and ADGM each mandate audited financials for licence renewal regardless of revenue. Mainland LLCs below AED 50 million with no free zone obligation have no statutory audit requirement, but most banks and investors require one before extending credit or capital.
Can the same firm do our bookkeeping and our audit?
No. Auditor independence under ISA prohibits the firm issuing the opinion from having prepared or maintained the records it is examining. This is called self-review threat. If we handle your bookkeeping, a different firm must audit. If we conduct your audit, a different firm must keep your books. Firms that offer both simultaneously are compromising the independence that gives the opinion its value.
What is the difference between unmodified, qualified, adverse, and disclaimer opinions?
Unmodified is clean -- the statements present a true and fair view. Qualified means one specific area has a material issue, but the rest is acceptable. Adverse means pervasive material misstatements make the entire set unreliable. Disclaimer means the auditor could not obtain sufficient evidence to form any opinion at all. Banks and free zone authorities treat anything other than unmodified as a red flag that requires explanation or remediation.
How much does a statutory audit cost in Dubai?
A single-entity audit for a mid-sized company with straightforward operations runs AED 15,000 to AED 40,000. Free zone entities with portal submission requirements sit at the mid-to-upper range. DIFC and ADGM audits tend higher due to full IFRS compliance and regulatory overlay. Consolidated group audits are scoped after reviewing the number of entities, jurisdictions, and intercompany complexity. The price reflects the hours of professional testing required, not a flat administrative fee.
What documents should we prepare before fieldwork begins?
We send a formal information request list during the planning phase. Core items include the signed trial balance, complete general ledger, all bank statements with reconciliations, fixed asset register with additions and disposals, accounts receivable and payable aging schedules, inventory records or count sheets, copies of significant contracts and lease agreements, board and shareholder meeting minutes, and a schedule of related-party transactions. The better organised this package is, the faster fieldwork finishes.
How long does an audit engagement take from start to finish?
Planning runs one to two weeks. Fieldwork at a company with current, reconciled books takes two to three weeks. Partner review and opinion drafting add another one to two weeks. Total engagement timeline is typically six to eight weeks for a single entity. If the records need cleanup before testing begins, add the cleanup period on top. Group audits run longer depending on subsidiary count and whether component auditors are involved.
What is a management letter and do we always receive one?
Yes. At the end of every engagement we issue a management letter documenting control deficiencies, process weaknesses, and accounting errors observed during fieldwork. Each finding is described with the specific risk it creates and a recommendation proportionate to your business size. The management letter is addressed to the board or managing director and is separate from the audit opinion. It is not published externally but is essential reading for anyone responsible for financial controls.
Why does the auditor need to attend our inventory count?
ISA 501 requires the auditor to attend physical inventory counting when inventory is material to the financial statements. The auditor performs test counts to verify that recorded quantities match physical quantities, inspects the condition of goods, and identifies obsolete or slow-moving stock. If the auditor is not present during the count, they must perform alternative procedures to obtain sufficient evidence -- and those alternatives are harder and less reliable than being there.
What happens if the auditor finds a material error?
We discuss it with management first. If the error is corrected and the financial statements are adjusted before signing, the opinion is unaffected. If management refuses to correct a material misstatement or cannot provide sufficient evidence to resolve it, the opinion is modified -- qualified if the issue is isolated, adverse if it is pervasive. Our role during fieldwork is to find issues early enough that they can be resolved, not to document them after the damage is done.
Does our auditor need to be on the DMCC Approved List?
If your company is registered in DMCC, yes. The DMCC Member Portal rejects audit reports signed by firms not on its Approved Auditors List. Similarly, DIFC requires auditors registered with the DFSA or licensed by the DIFC Authority. ADGM has its own approved auditor requirements. Mainland companies audited for corporate tax purposes can use any Ministry of Economy-registered firm. We hold the Ministry of Economy registration and appear on the DMCC Approved Auditors List.
How does the audit affect our corporate tax filing?
For entities above the AED 50 million threshold, tax groups, and qualifying free zone persons, the corporate tax return starts from the accounting profit figure in the audited statements. Any audit adjustments change that starting point and flow into the taxable income computation. If the statements and the return show different profit figures, the FTA will ask why. The audit is no longer a standalone exercise -- it is the foundation your tax position is built on.
Can we switch auditors mid-engagement or after a bad experience?
You can appoint a new auditor at any time, subject to your articles of association and any free zone authority notification requirements. The incoming auditor will request access to the prior firm's working papers and communicate with them as required by ISA 510. If you are switching because of a qualification or a dispute, be prepared to explain the reason to your new auditor -- they are required to understand why the change happened. We accept transitioning clients and handle the predecessor communication professionally.
Still have questions? We're here to help.
Call Us Now