IFRS Compliance
in Dubai
Your auditor qualified the statements. Your bank wants IFRS financials before renewing the facility. Your free zone authority rejected the filing. We fix the gap and keep it fixed.
MINISTRY OF ECONOMY REGISTERED PRACTICE
- Gap Analysis
- First-Time Adoption
- Ongoing Reporting
Financials That Pass the Test They Were Written For
IFRS is not a formatting exercise -- it changes the numbers on your balance sheet.
Statements Banks Accept
Lenders reject non-IFRS financials. We produce statements in the format banks and investors expect, with the disclosures they actually read.
Audit Without Qualifications
A qualified opinion follows your company for years. We structure the books so your auditor signs clean the first time.
Corporate Tax That Ties Back
The FTA expects financial statements aligned with IFRS. When your taxable income computation starts from IFRS profit, the trail must be airtight.
One Conversion, Not Annual Rework
We build IFRS into your chart of accounts and accounting policies permanently. Next year's financials come out compliant by default, not through another consulting project.
From Gap Analysis to Signed Statements
IFRS compliance is a sequence of specific technical steps, not a general promise of better reporting.
IFRS Gap Analysis
Line-by-line comparison of your current accounting policies against applicable IFRS standards, with quantified impact on each financial statement.
First-Time Adoption (IFRS 1)
Opening balance sheet preparation, exemption elections, restated comparatives, and the reconciliation disclosures IFRS 1 requires.
Revenue Recognition (IFRS 15)
Five-step model applied to your contracts -- performance obligations identified, transaction prices allocated, and revenue timing adjusted.
Lease Accounting (IFRS 16)
Right-of-use assets and lease liabilities recognised on the balance sheet for every qualifying lease, with depreciation and interest schedules.
Financial Instruments (IFRS 9)
Classification, measurement, and expected credit loss provisioning for receivables, investments, and any hedging arrangements.
Chart of Accounts Restructure
Account codes and groupings redesigned to map directly to IFRS presentation requirements without manual reclassification at year-end.
Accounting Policy Manual
Written policies for revenue recognition, leases, impairment, provisions, and every other standard that touches your business -- auditor-ready.
Disclosure Drafting
Notes to the financial statements drafted to IFRS disclosure checklists, covering every required and material voluntary disclosure.
Comparative Period Restatement
Prior-year financials restated under IFRS so your first compliant statements include the comparatives auditors and regulators require.
IFRS 18 Preparation
Income statement restructured into the three mandatory categories -- operating, investing, financing -- ahead of the January 2027 effective date, with 2026 comparatives built now.
Ongoing IFRS Reporting
Monthly or quarterly financials maintained to IFRS throughout the year so compliance is continuous, not a year-end conversion.
Standards Work Is All We Do Differently
Ahmed Mahfoudh Chartered Accountants & Auditors is a Dubai practice registered with the UAE Ministry of Economy. We handle IFRS compliance for mainland LLCs, free zone entities, and branches of foreign companies -- from gap analysis through ongoing monthly reporting. Because we also run the bookkeeping and audit preparation in-house, IFRS is not layered on top of someone else's ledger. It is built into the chart of accounts from the first entry. When a new standard takes effect or an amendment changes a measurement rule, we update the policies and the books in the same engagement.
What Goes Wrong With IFRS in Practice
Most non-compliance is not intentional -- it is a gap nobody measured until the auditor pointed at it.
We Measure the Gap Before We Start Work
A gap analysis is not a sales pitch for a bigger engagement. It is a line-by-line technical comparison that tells you exactly which standards your current financials violate, by how much, and what the restatement impact is. You see the scope before you commit to anything. Some gaps are small. Some rewrite your balance sheet.
IFRS Lives in Your Chart of Accounts
We do not maintain a set of management accounts and then reclassify to IFRS at year-end. We restructure your chart of accounts so every transaction posts to IFRS-compliant codes from day one. That eliminates the annual conversion exercise and the errors that come with it.
Lease Accounting Is Where Most Companies Trip
IFRS 16 moved operating leases onto the balance sheet. A Dubai trading company with a warehouse lease suddenly has a right-of-use asset and a liability that affects its debt covenants. We calculate the lease schedules, post the entries monthly, and flag any covenant impact before your bank does.
Revenue Recognition Has Real Consequences
Under IFRS 15, revenue is recognised when control transfers, not when you invoice. For companies with long-term contracts, milestone billing, or bundled deliverables, the timing of recognised revenue can shift materially. We apply the five-step model to your actual contracts so the P&L reflects reality, not billing dates.
We Prepare for IFRS 18 Now, Not in 2027
IFRS 18 replaces IAS 1 in January 2027 and requires a three-category income statement with a defined operating profit line. But the 2027 statements need 2026 comparatives in the new format. If you wait until 2027 to restructure, you are already behind. We build the dual presentation into this year's close.
The Policies Are Documented, Not in Someone's Head
Every IFRS accounting policy we apply is written in a formal policy manual tied to the specific standards your business falls under. When your auditor asks why revenue is recognised at a certain point or how you measure expected credit losses, the answer is in a document, not a conversation.
Your IFRS Compliance Team
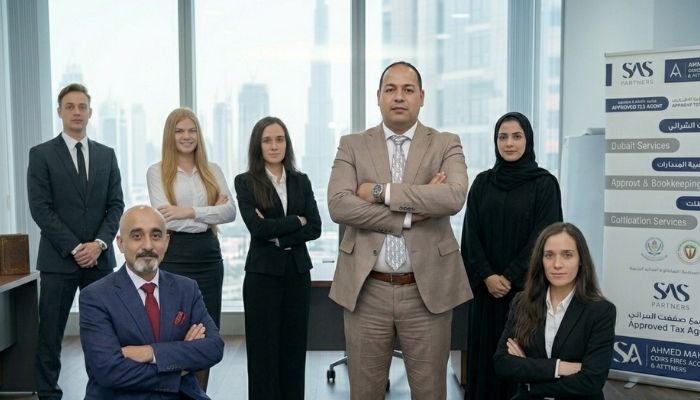
Chartered accountants who apply these standards daily, not consultants who advise on them annually.
Sameh Abdalla
CEO & Founder
Sami Abdallah leads the firm with expertise in accounting, audit, tax advisory, and consulting. He provides strategic guidance and supports long-term business growth across the UAE.
Ahmed Mahfoudh
Audit Manager
Ahmed Mahfoudh manages audit assignments and financial reviews with a focus on accuracy, compliance, and risk assessment. He delivers clear insights to strengthen financial control.
Ahmed Elbadawi
Legal Manager
Ahmed Elbadawi provides legal guidance, contract management, and compliance support. He helps protect business interests, reduce risks, and ensure smooth legal operations.
Ahmed Samir
Tax Manager
Ahmed Samir specializes in UAE VAT, corporate tax, and compliance services. He supports businesses in managing tax obligations while improving financial efficiency and compliance effectively.
What Finance Teams Say After Achieving Compliance
Financial controllers, CFOs, and directors in Dubai who moved from qualified opinions to clean statements.
“Their IFRS support removed the uncertainty we faced with complex reporting standards. Statements are now accurate, aligned, and audit-ready without last-minute pressure.”
“Switching to proper IFRS felt overwhelming until we engaged this team. They guided us step by step and delivered clean compliant financials our auditors accepted without issues.”
“Clear expertise in IFRS standards and practical application for Dubai companies. The detail and consistency has strengthened our financial credibility with banks and investors.”
“They translate complex IFRS rules into straightforward processes. Our financials now meet international standards while remaining easy for management to review.”
“From initial gap analysis to compliant reporting, their IFRS service was thorough and reliable. We gained technical accuracy and greater confidence in our published figures.”
“Precise and focused on real business needs. Their IFRS work has elevated our reporting quality and made regulatory reviews far smoother than before.”
Before You Start an IFRS Engagement
Technical questions finance teams ask when they know compliance is overdue.
Is IFRS mandatory for all UAE companies?
Not universally, but in practice most companies need it. Free zones like DMCC, JAFZA, and DAFZA mandate IFRS-compliant audited financials. The corporate tax regime requires financial statements that align with IFRS. Banks and investors increasingly refuse non-IFRS statements. If you interact with any of these stakeholders, IFRS is not optional.
What is a gap analysis and how long does it take?
A gap analysis compares your current accounting policies and financial statements against every IFRS standard that applies to your business. It quantifies the impact -- how much your assets, liabilities, revenue, or equity change under IFRS. For a mid-sized company, this takes two to four weeks and produces a report with specific restatement amounts.
What does first-time IFRS adoption involve?
Under IFRS 1, you prepare an opening balance sheet at your transition date, elect which optional exemptions to apply, restate at least one comparative period, and produce reconciliation disclosures showing the differences from your previous framework. The full adoption process typically takes four to six months from gap analysis to signed financial statements.
Which standards cause the most trouble?
IFRS 16 (leases), IFRS 15 (revenue), and IFRS 9 (financial instruments). IFRS 16 puts operating leases on the balance sheet and can trigger debt covenant issues. IFRS 15 changes when revenue is recognised for multi-deliverable contracts. IFRS 9 requires expected credit loss provisions on receivables before any customer actually defaults.
How does IFRS affect our corporate tax return?
Your taxable income computation starts from accounting profit. If that profit is measured under IFRS, the adjustments for corporate tax -- exempt income, disallowed expenses, timing differences -- must reconcile back to IFRS figures. Non-IFRS financials create a disconnect that the FTA can challenge during review.
What is IFRS 18 and do we need to act now?
IFRS 18 replaces IAS 1 from January 2027. It requires a new income statement format with mandatory operating, investing, and financing categories and a defined operating profit line. Your 2027 financials need 2026 comparatives in the IFRS 18 format. That means structuring 2026 data now, not retrofitting it next year.
What does this cost?
A gap analysis for a single-entity mid-sized company runs AED 15,000 to AED 40,000 depending on complexity. Full first-time adoption -- gap analysis through signed financials -- ranges from AED 80,000 to AED 200,000, depending on how many standards require restatement and how clean your existing records are. Ongoing IFRS reporting is priced as part of a monthly accounting retainer.
Can you fix a qualified audit opinion?
Usually, yes. A qualification typically stems from a specific IFRS departure -- unrecognised lease liabilities, incorrect revenue timing, missing disclosures. We identify the exact standards behind the qualification, restate the affected items, and work with your auditor to resolve it. The goal is a clean opinion in the next reporting period.
Do we need to change accounting software?
Rarely. IFRS compliance is about how transactions are classified and measured, not which software records them. We restructure your chart of accounts and posting rules within your existing system -- QuickBooks, Zoho, Xero, or Tally. An ERP migration is only necessary if your current system cannot handle the required account structures or multi-period reporting.
Can we adopt IFRS for SMEs instead of full IFRS?
IFRS for SMEs is a simplified framework with fewer disclosures and simpler measurement rules. It is accepted by some free zones and sufficient for many private companies. However, if your free zone mandates full IFRS, or your bank or investor requires it, the simplified version will not satisfy them. We assess which framework fits before recommending.
How long until our financials are compliant?
From engagement start to signed IFRS-compliant financial statements, the typical timeline is four to six months for a first-time adoption. Ongoing compliance after that is built into the monthly accounting cycle. If your books are clean and your transactions are straightforward, the timeline compresses. If there is a backlog or complex contracts, it extends.
What if we only need help with one standard?
We scope engagements to exactly what is needed. If your only issue is IFRS 16 lease accounting, we calculate the lease schedules, post the entries, and draft the disclosures without touching the rest of your financial statements. Single-standard engagements are common and priced accordingly.
Still have questions? We're here to help.
Call Us Now